US common stocks / ADRs: top 10 by volume; top 10 gainers (by % change, volume as tie-breaker); top 10 losers (by % change, prefer liquid names). Deep notes cover the de-duplicated set across the three boards.
30 names on this page · volume 10 · gainers 10 · losers 10
Order: volume board → gainers → losers; each ticker appears once. Summaries of public information only — please verify primary sources.
1/10SPCX SPCX
+9.65%
Close 146.15 · Vol 166.00M · Type: Squeeze / float
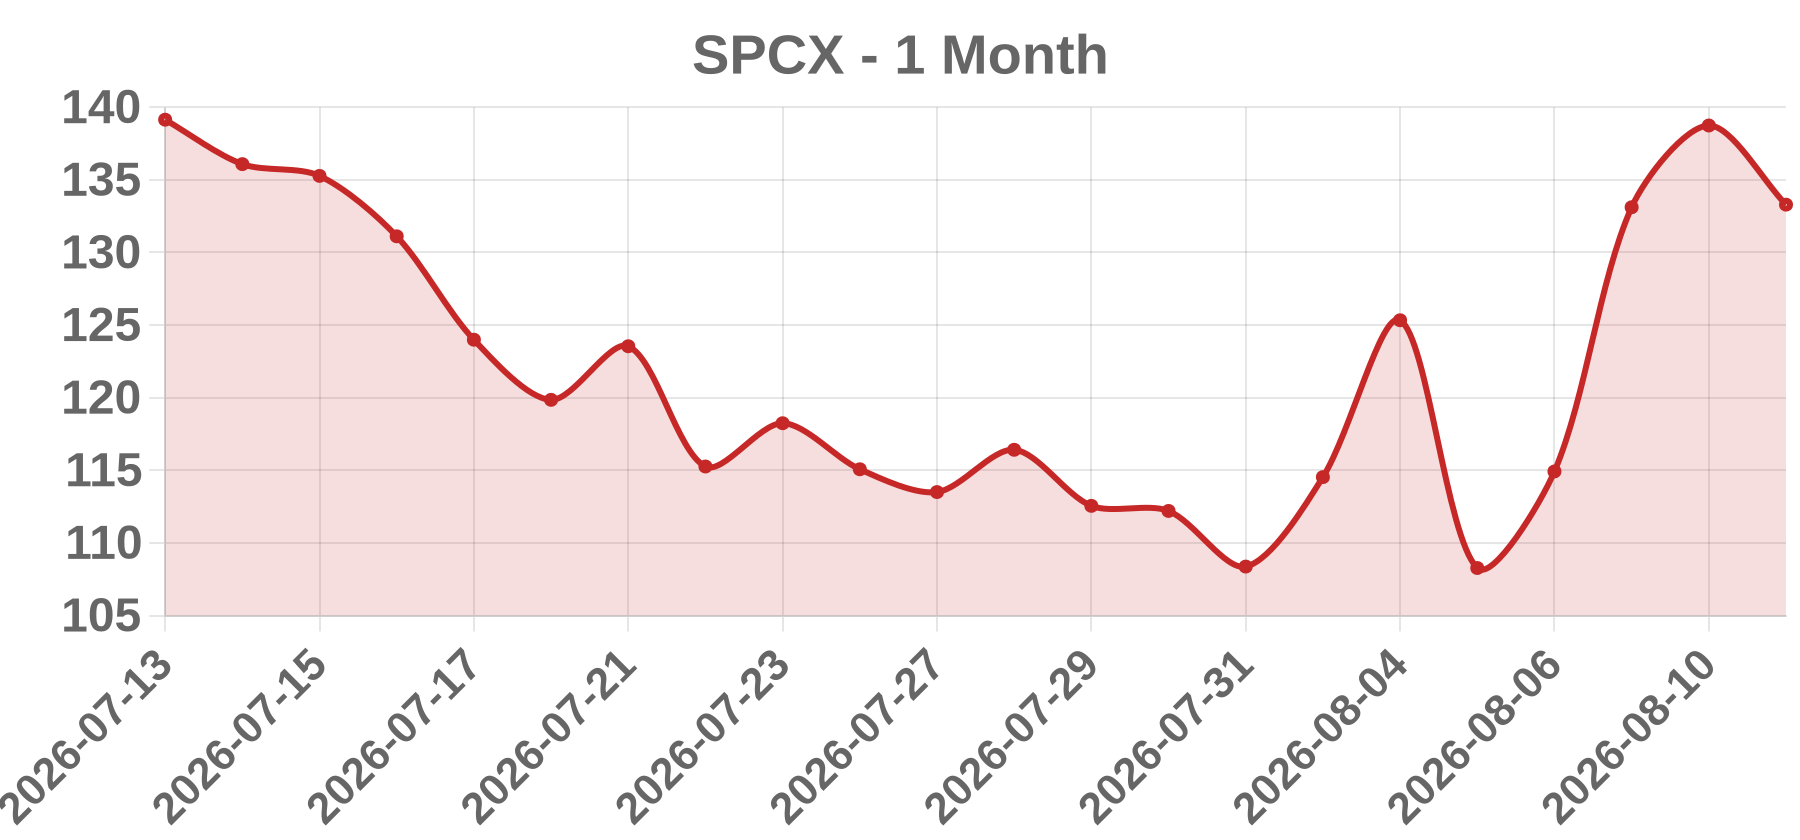
Approx. 1-month price (illustrative)
Business Space Exploration Technologies Corp. (SPCX, Nasdaq), Elon Musk's aerospace and AI giant, operates launch services (Falcon 9/Heavy, Starship), Starlink satellite internet (~12M subscribers), and SpaceXAI (Grok models, AI cloud/compute), plus U.S. defense programs such as the $185B Golden Dome. It listed on June 12, 2026 at $135.00/share in the largest IPO in history.
Today’s take SPCX opened at its $135 IPO price, dipped to $134.01, then surged to a $149.60 high before closing at $146.15 (+9.65%), its highest close since July 10 and roughly 40% above the Aug 3 low of $104.83. The primary driver was forced short covering: S3 Partners (via CNBC) reported short interest collapsed from a 34% peak of float last week to about 11% by Aug 12, with MD Ihor Dusaniwsky saying shorts are 'out of bullets.' The Aug 6 lockup (912M shares) expanded the tradable float, mechanically cutting the short-interest ratio while supplying shares to cover. A same-day AI catalyst cluster compounded the squeeze: SpaceXAI launched Grok 4.6 ($2/$6 per million tokens), Musk's Aug 11 all-hands claimed AI revenue could top rockets plus Starlink by September and reach 99% of value in 4-5 years, the $60B Cursor/Anysphere deal neared closing, and Morgan Stanley reiterated Overweight ($300 base, $600 bull). Institutional validation came from Capital Research's new ~$1.8B 13F position and NBIM's first-ever ~$1.2B SpaceX stake.
Business Super Micro Computer, Inc. (NASDAQ: SMCI) designs and manufactures high-performance, application-optimized server, storage, and AI/GPU compute systems built on a modular 'Data Center Building Block Solutions' (DCBBS) architecture, including liquid- and air-cooled AI servers, rack-scale solutions, and 5G/edge embedded platforms. Headquartered in San Jose, CA, and an S&P 500 / Nasdaq-100 constituent with ~6,238 employees, the company generated ~$39.1B revenue in FY2026 (+78% YoY), driven by AI infrastructure demand from hyperscalers and enterprise customers.
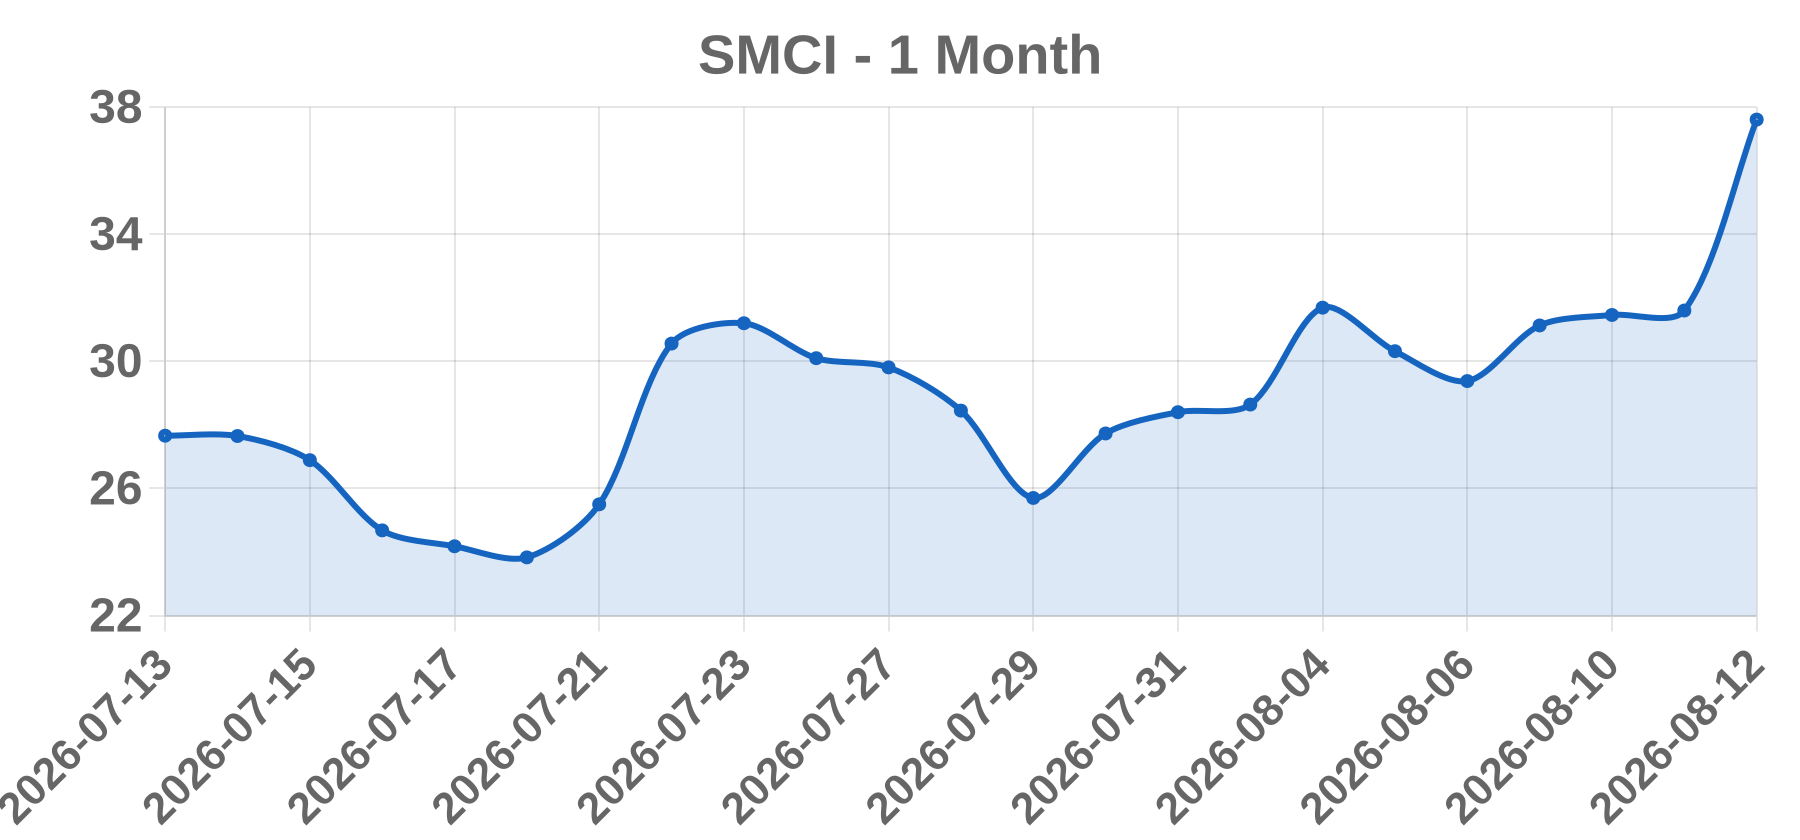
Today’s take SMCI's +19.02% surge on Aug 12, 2026 followed Q4 FY2026 results reported after the close on Aug 11. Non-GAAP EPS of $1.70 crushed consensus of $0.62-$0.96 (Benzinga/Barron's), while revenue of $11.12B (+93% YoY) modestly missed the ~$11.3-$12.3B Street range. The true catalyst was margin and guidance: non-GAAP gross margin of 17.6% more than doubled the company's own 8.2%-8.4% guided range, and FY2027 revenue guidance of $65B-$72B (midpoint $68.5B) blew past the ~$54.4B consensus. CEO Charles Liang cited >$60B in new orders and record backlog entering FY2027, ~70% pure AI. A wave of price-target hikes (Rosenblatt $51, Needham $46, Wedbush $40, Bernstein $42, Citi/Barclays $39, Mizuho $35, BofA $33, Goldman $34) extended the rally intraday to $38.15 before the stock faded to close $37.61. Skeptics (BofA Underperform, Citi High-Risk) flagged FY2026 operating cash flow of -$6.8B and Q1 margin guidance of ~10.6%.
Business Intel Corporation (NASDAQ: INTC), headquartered in Santa Clara, California, is the world's leading microprocessor designer and manufacturer, spanning Core PC processors, Xeon data-center/server CPUs, and Gaudi AI accelerators. Under CEO Lip-Bu Tan, Intel is executing a turnaround centered on Intel Foundry, its contract-manufacturing business targeting leading-edge 18A/14A nodes in direct competition with TSMC. The stock had risen ~164% YTD through Aug 12, 2026.
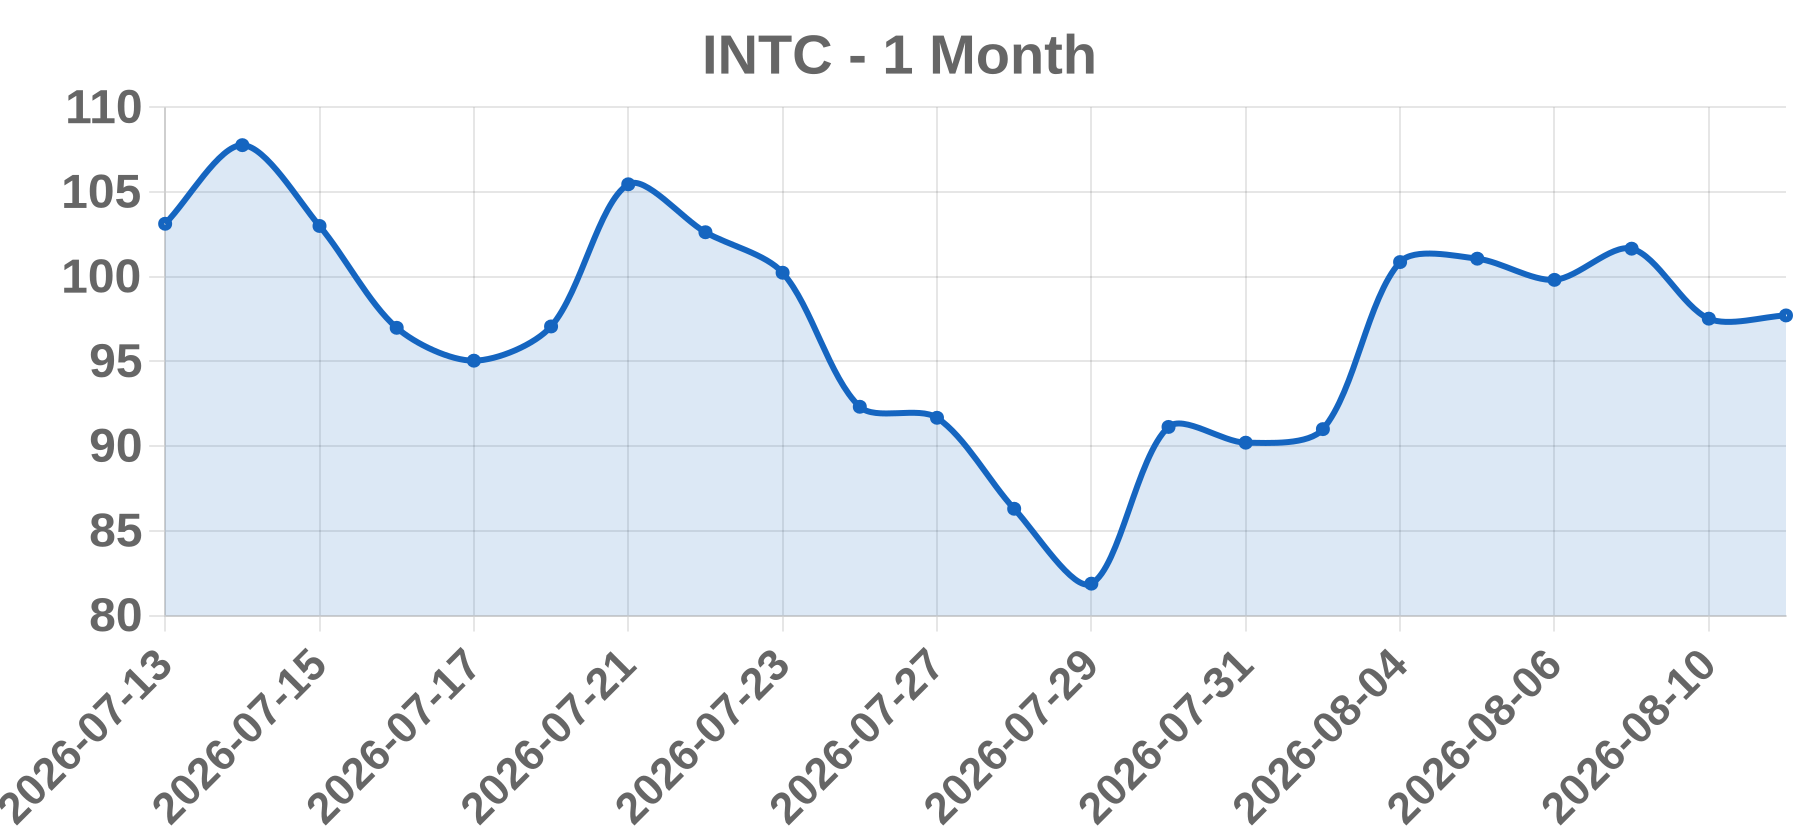
Today’s take On Aug 12, 2026, INTC closed at $100.95, +3.32% (intraday high $103.16) on ~160.7M shares, recovering from the prior sessions' dilution-driven slide. Sequence: Aug 10 the company announced a $15B common-stock offering (shares fell 4.06%); Aug 11 the deal was upsized to $20B and priced at $95/share (210.5M shares, ~4.2% dilution, ~$19.7B net proceeds, ~$100B demand per Bloomberg). On Aug 12, BofA Securities' Vivek Arya reiterated Buy, trimming the price objective to $145 from $160 (~48% upside) and calling the raise a 'net positive' — evidence of management conviction in the foundry strategy. UBS (Timothy Arcuri) reiterated Neutral with a PT cut to $112 from $121 but framed the raise as removing the share-supply overhang. Macro tailwind: July CPI printed +3.4% y/y (in line, down from 3.5%) with core +2.5% (down from 2.6%), cutting September Fed-hike odds to ~36-44% (CME FedWatch); the PHLX Semiconductor Index rose >3% with Micron +4.9% and AMD +1.8%. The session showed a classic 'sell the announcement, buy the analyst endorsement' pattern.
Business Nokia Oyj is a Finnish public limited company headquartered in Espoo, Finland, trading as American Depositary Receipts on the NYSE under NOK (primary listing: Nasdaq Helsinki). It is a B2B network infrastructure and technology company organized into four segments: Mobile Networks; Network Infrastructure (Optical, IP and Fixed Networks); Cloud and Network Services; and Nokia Technologies (patent licensing). Led by CEO Justin Hotard, Nokia completed the ~$2.3B acquisition of Infinera in Feb 2025 to become a vertically integrated optical-networking supplier, and in Aug 2026 agreed to buy NXP's Arizona fab to build indium-phosphide optical chip capacity.
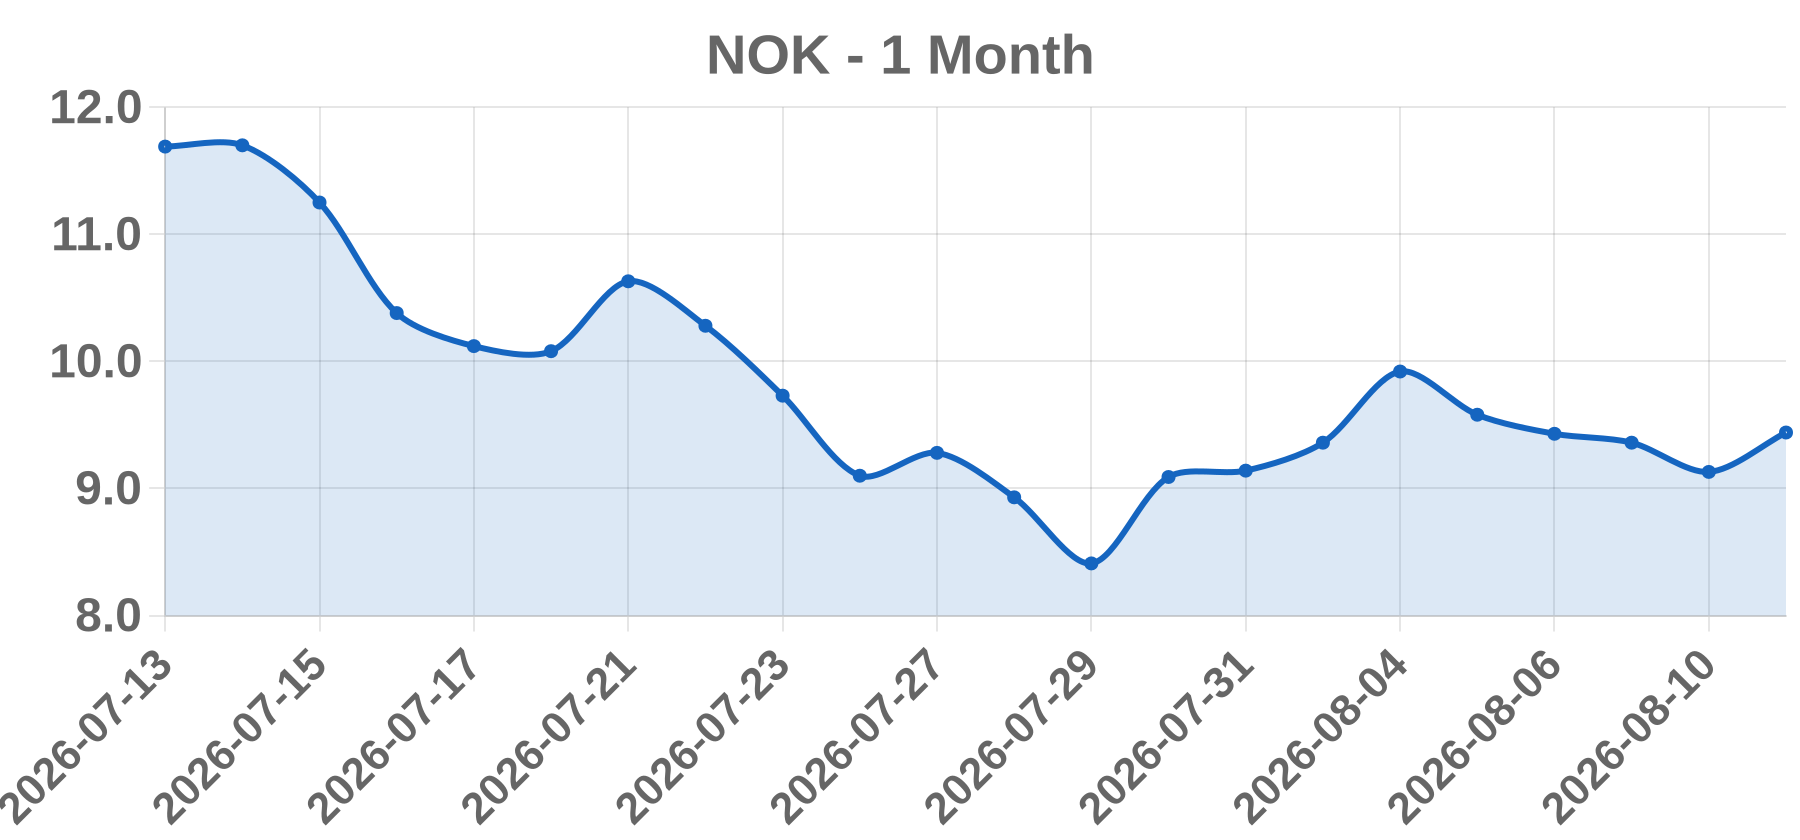
Today’s take The catalyst was external, not company-specific. Lumentum (LITE) reported fiscal Q4 2026 revenue of $1.01B (+109% y/y, above ~$988M consensus) and adjusted EPS of $3.23 (vs. ~$2.99 est.), guiding FQ1 to a $1.25B midpoint (+23.8% q/q) — evidence that AI data-center optical demand still outpaces supply. The read-through re-rated the entire optical complex (LITE +14%, Ciena +11%, Celestica +9%) and Nokia closed +9.32% at $10.32, adding ~$5.0B (€4.35B) in market value — about 3.1x the €1.4B of near-term AI/cloud order conversion Nokia guided toward. Supporting narratives: a draft FCC ban on Chinese optical transceivers (Reuters), Nokia's own Q2 beat (AI & Cloud sales up 105% to €446M, €2.8B order intake, FY26 guidance raised to €2.1–2.6B), and analyst target hikes (BofA $18.50 Buy, SEB Buy, JPMorgan $21). Caveats: no new Nokia contract was announced, trailing P/E is elevated, reported Q2 operating loss was -€50M on restructuring, and shares remain ~41% below the $17.45 52-week high.
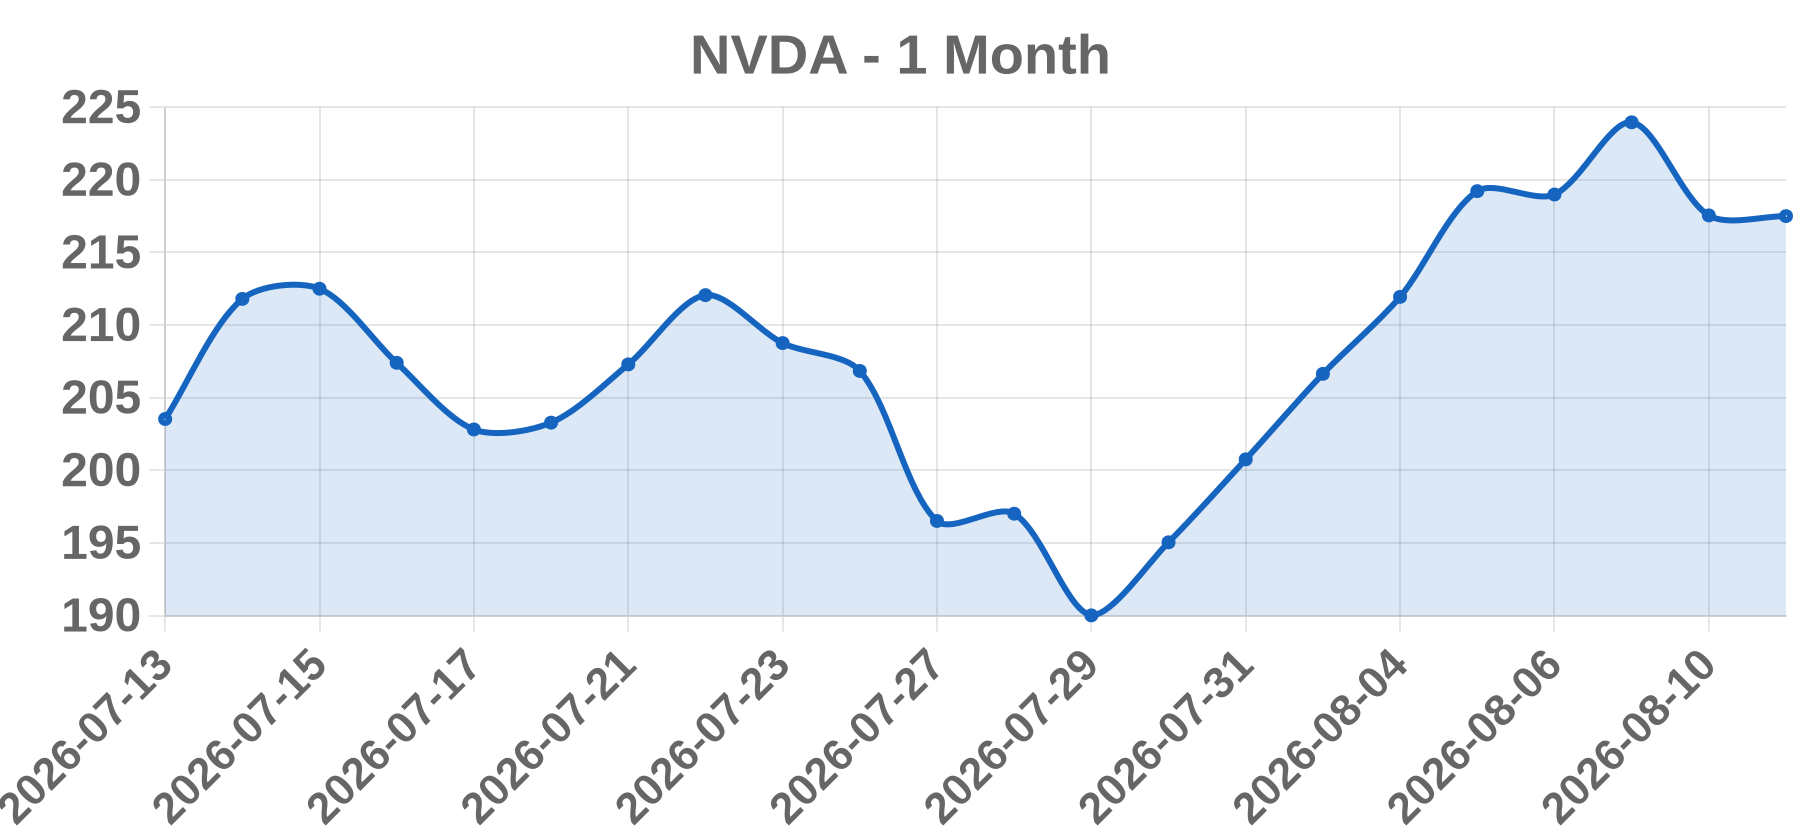
Business NVIDIA Corporation is a Delaware-incorporated company headquartered in Santa Clara, California, listed on the Nasdaq Global Select Market (ticker: NVDA) and a component of the S&P 500 and Dow Jones Industrial Average. It is the world's largest semiconductor company by market capitalization (~$5.44 trillion as of Aug 12, 2026). Its primary business is designing GPUs and accelerated-computing platforms for AI data centers (Hopper, Blackwell, and Vera Rubin generations), the CUDA software ecosystem, DGX AI-factory systems, and high-speed networking (NVLink, InfiniBand, Ethernet), with additional markets in gaming, professional visualization, automotive, and robotics.
Today’s take NVIDIA closed +3.03% at $224.09 (+$6.59), its best close since June 2, adding roughly $159B in market cap to ~$5.44T. The advance was a multi-catalyst sector/macro rally. The immediate trigger was Super Micro's blowout FQ4 report (non-GAAP EPS $1.70 vs. $0.96 consensus; revenue $11.12B, +93.2% YoY; $60B+ new orders and record backlog; FY27 guidance $65–72B; SMCI +19%), re-underwriting AI accelerator demand ahead of NVDA's Aug 26 FQ2 print. An in-line July CPI (+3.4% YoY, core +2.5%) eased September rate-hike fears, lifting the Nasdaq +0.54%. The PHLX Semiconductor Index opened +3.5%, with TSMC +2.4%, Micron +4.9%, AMD +2.8%, Broadcom +2.2%, ASML +2.4%, plus Samsung +6.7% and SK hynix +4.5% in Korea. Follow-through from the Aug 10 announcement mobilizing $500B+ of third-party AI-infrastructure capital with Apollo, BlackRock, Blackstone, Brookfield, Goldman Sachs and KKR, same-day bullish reiterations (Goldman Buy $285; Susquehanna Buy $275; Wells Fargo Overweight $315; BofA Buy $350), reports of the ~1-trillion-parameter Nemotron 4 open model, and Foxconn's Q4 Vera Rubin shipments all aligned. NVDA had risen ~12% over two weeks into earnings.
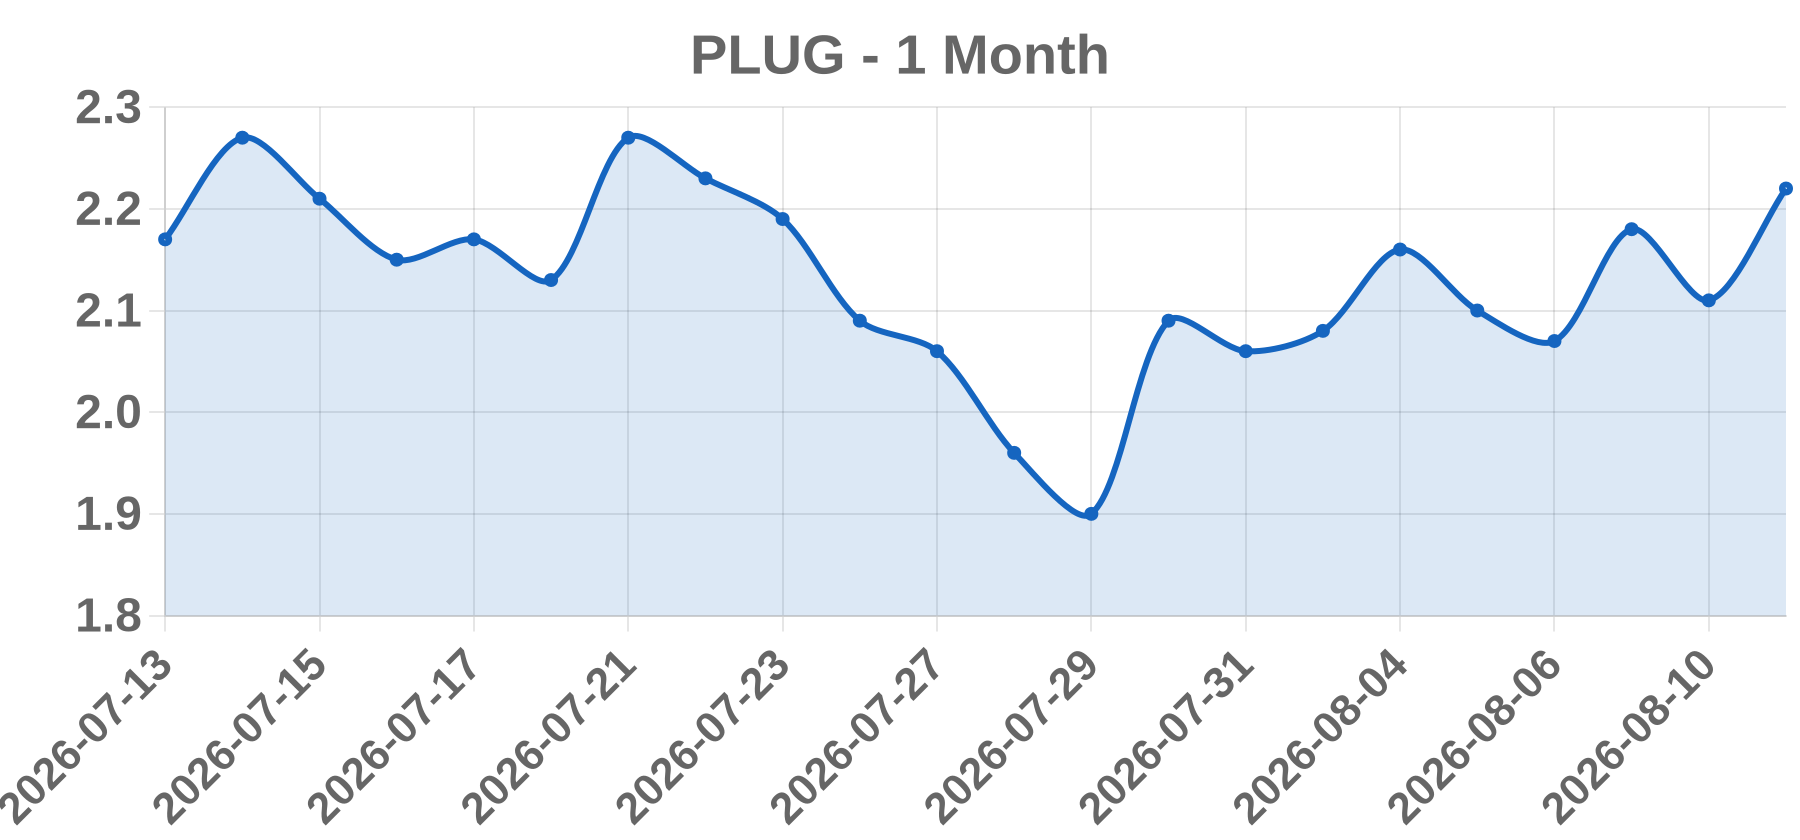
Business Plug Power Inc. (NASDAQ: PLUG), founded in 1997 and headquartered in Slingerlands, New York, designs, builds, and operates a vertically integrated hydrogen ecosystem spanning production, storage, delivery, and power generation. Its core offerings include GenDrive PEM fuel-cell systems for material-handling equipment, GenFuel liquid-hydrogen fueling infrastructure, GenKey turnkey solutions, GenCare service, and GenEco PEM electrolyzers, serving customers such as Walmart, Amazon, Home Depot, BMW, and BP.
Today’s take The Aug 12 gain was the tail of a beat-and-raise Q2 FY2026 earnings catalyst reported Aug 10 after close. Revenue of $178.3M (+9% QoQ, +2.5% YoY) beat the ~$169.4M consensus by nearly $10M; adjusted EPS of -$0.07 beat the -$0.08 estimate and improved from -$0.18 a year ago. Gross margin swung to ~breakeven (-0.9%) from -31% in Q2 2025 and -13% in Q1 2026, while operating expenses fell ~50% YoY to ~$62M and net cash usage dropped ~58% QoQ to ~$61M. Management raised FY2026 revenue growth guidance to 15-16% (from 13-15%) and reaffirmed a positive Q4 2026 EBITDAS target; 1,666 GenDrive units were deployed (+125% YoY) and service revenue rose 82% to ~$30M. After surging ~17.5% intraday on Aug 11 before closing +5.21%, shares added +3.15% to $2.29 on Aug 12, aided by Roth MKM reiterating Buy with a $3.50-$5.00 target. Risks: unrestricted cash fell to ~$162M, weighted-average share count rose ~23.5% YoY, and 20-analyst consensus remains Hold with a wide $1.30-$7.00 target range.
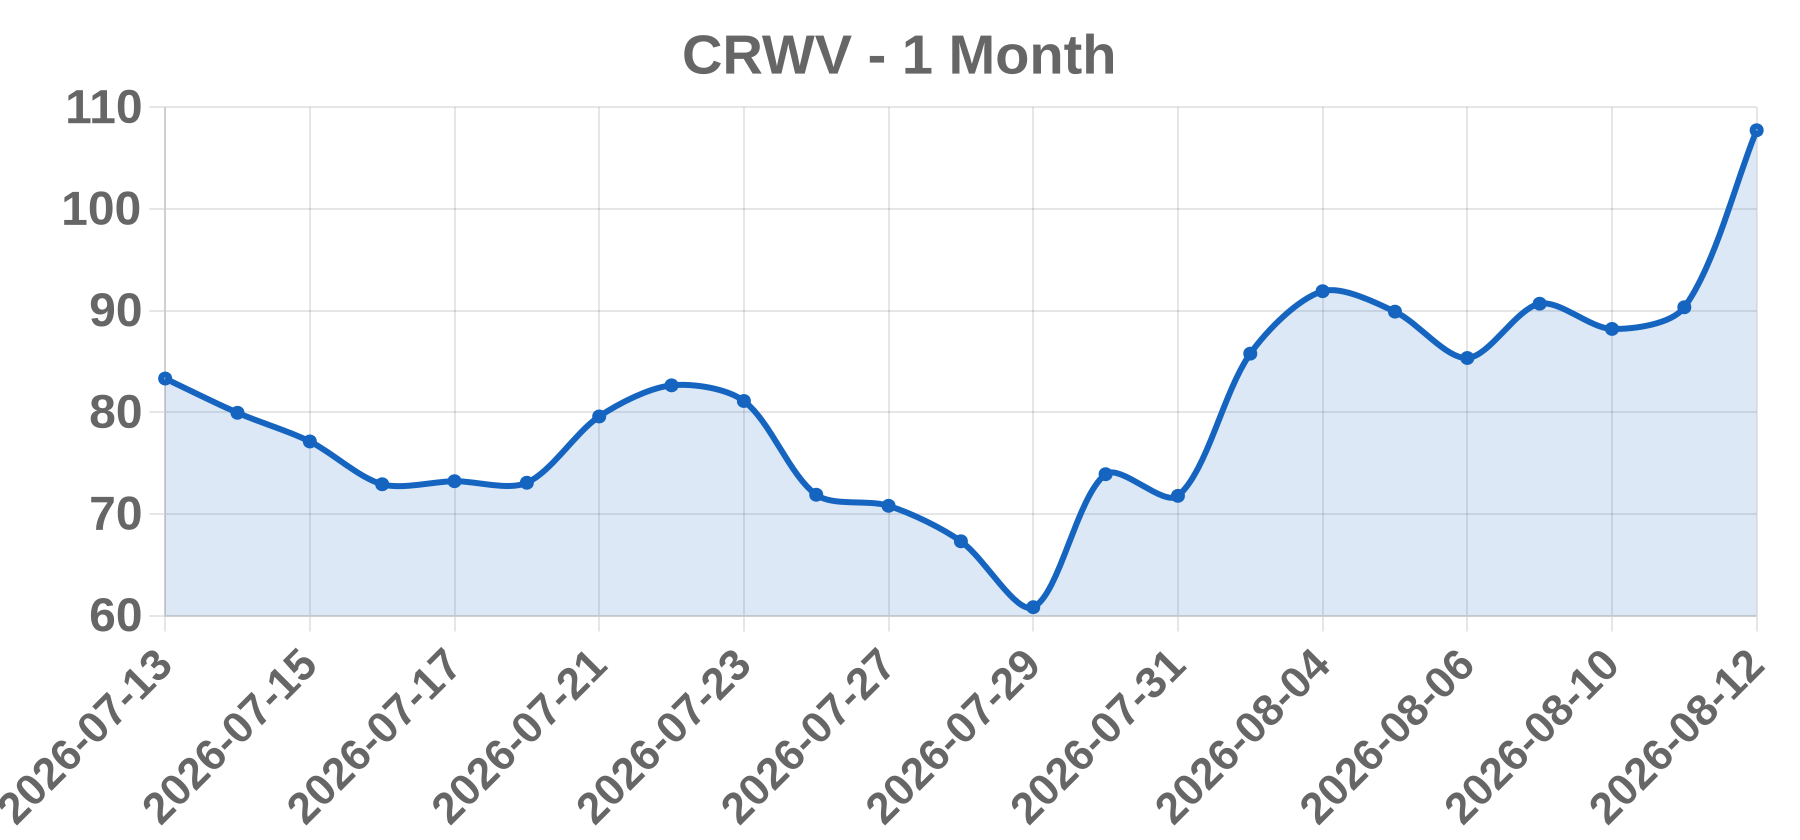
Business CoreWeave, Inc. (Nasdaq: CRWV) is an AI hyperscaler ('neocloud') headquartered in Livingston, New Jersey, that owns and operates NVIDIA GPU-based data centers, renting raw compute, managed training/inference services and AI software tooling to AI labs, hyperscalers and enterprises including OpenAI, Meta, Microsoft and Anthropic. The company listed on Nasdaq in March 2025.
Today’s take CRWV surged +19.28% to $107.73 on Aug 12, 2026 after Q2 FY2026 results (reported Aug 11 after the close) crushed expectations. Revenue rose 112% YoY to $2.575B (vs ~$2.56B consensus); GAAP loss per share of -$1.14 was narrower than the ~-$1.41 consensus; adjusted operating income of $128M beat the ~$66M estimate; revenue backlog hit ~$104B (up 246% YoY), excluding >$25B of new customer commitments signed in early Q3. FY2026 revenue guidance was raised to $12.4B-$13.2B with adjusted operating income of $960M-$1.15B, and Q3 revenue guidance of $3.45B-$3.6B topped estimates. Management cited effectively sold-out near-term capacity and ~25% July price increases. The beat ignited a short squeeze: short interest was ~64.4M shares (~19% of float, 7/15/26) and CRWV ranked among Hazeltree's top-10 most shorted names. Sell-sides raised targets — Truist $155, Piper Sandler $153, Baird $130, Wells Fargo $160 — while peers Nebius (+28-34%), IREN and Micron (+4%) rallied, aided by a tame July CPI print.
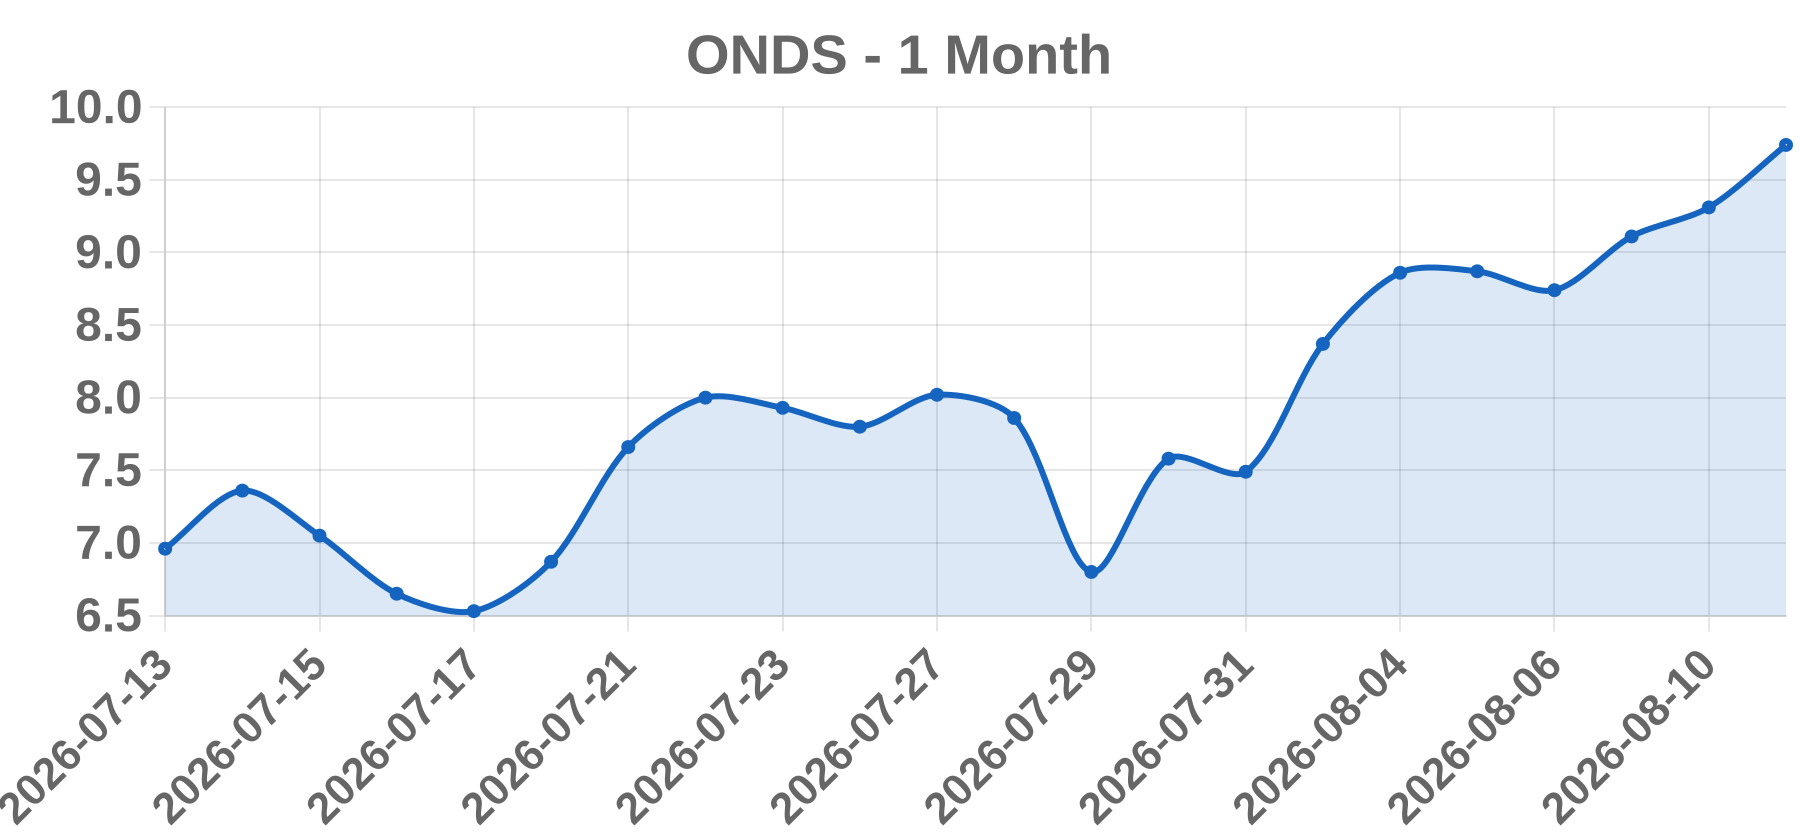
Business Ondas Inc. (NASDAQ: ONDS; formerly Ondas Holdings, renamed January 2026; HQ West Palm Beach, FL; ~495 employees) is a provider of autonomous systems, robotics, and mission-critical wireless technologies for defense, homeland security, public safety, critical infrastructure, and industrial markets. It operates through Ondas Networks (private mission-critical wireless broadband) and Ondas Autonomous Systems (drones, counter-UAS, and defense platforms), and has been transformed by ~14 acquisitions (DZYNE, Cyberhawk, Mistral, Sentrycs, etc.) into an autonomous-defense platform.
Today’s take ONDS closed flat at $9.77 (+0.31%) on Aug 12 on ~83-87M shares, a top Nasdaq active, as investors positioned for Q2 results due Aug 13, 8:30 ET. Consensus is ~$68.0-68.5M revenue (+~978% YoY, +37% QoQ) and a -$0.095/-$0.10 EPS swing after Q1's surprise $0.81 print (boosted by a $389.6M noncash warrant gain). The swing factor is the $525M FY26 target, which requires ~$406M in H2 (~$203M/quarter, ~3x the Q2 estimate) — a high-stakes prove-it setup driving two-way volume. No company-specific headline hit Aug 12 itself, but the news tape was dense: Cyberhawk closed Aug 10 ($118.2M cash plus 581,732 shares), Roth initiated Buy/$13 PT Aug 11, Israel MoD 'Digital Bat' award Aug 11, plus U.S. Army >$50M and AFRL >$6M awards. With ~44% of float shorted (229.6M shares, Jul 15) and 9/9 analysts at Buy (mean PT ~$19.06), the tight $9.65-9.99 range reflects consolidation before a binary event; after-hours rose to $10.00.
Business Hertz Global Holdings, Inc. (NASDAQ: HTZ) is a global vehicle rental and mobility company headquartered in Estero, Florida, operating under the Hertz, Dollar, and Thrifty brands through Americas RAC and International RAC segments, plus vehicle leasing and fleet services. Market capitalization was roughly $998M at the Aug 12, 2026 close, with a float of about 162M shares.
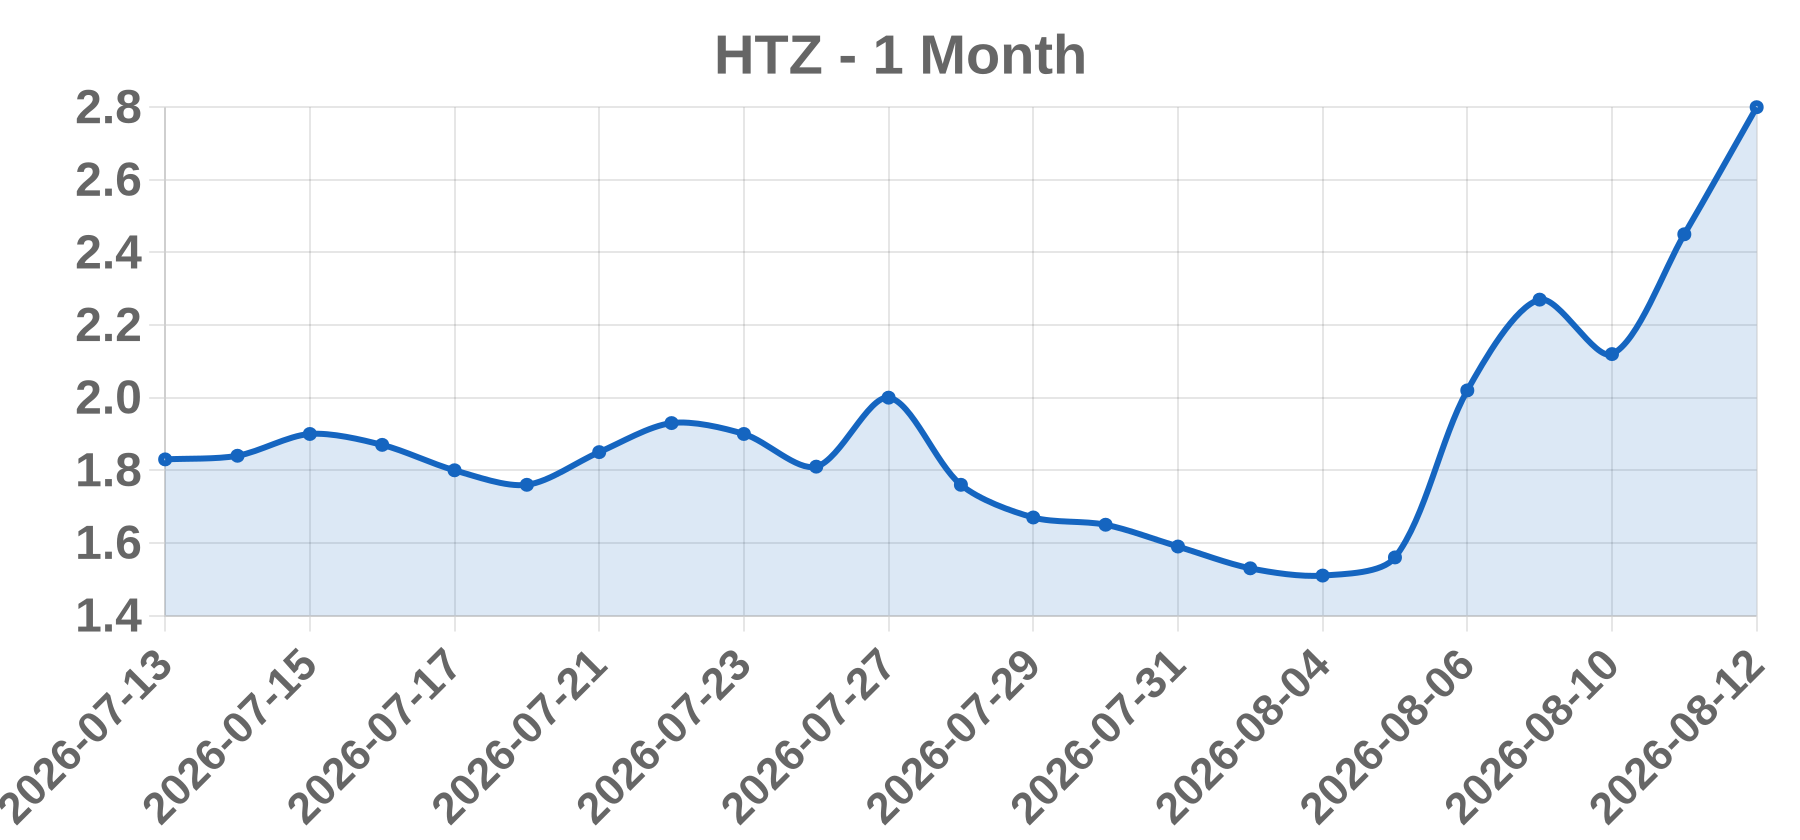
Today’s take HTZ closed +14.29% at $2.80 on Aug 12, 2026, the third double-digit up-session of a squeeze ignited by the Aug 6 Q2 2026 earnings beat (revenue $2.396B, +9.7% YoY; adjusted EPS -$0.11 vs -$0.25 est.; adjusted corporate EBITDA $81M vs $18M a year earlier). The rally resumed after a -6.6% pullback on Aug 10: +15.6% on Aug 11 and +14.3% on Aug 12, with the stock accelerating from a $2.38 intraday low to a $2.86 high before closing at $2.80. Same-day fuel came from fresh FINRA short-interest data (July 31 settlement) showing 103.2M shares short - roughly 78% of float, up 5.8% from July 15 - with about 6 days-to-cover. EquiLend showed borrow utilization above 90% since July 21 (95% on Aug 5) and financing costs near 300 bps. HTZ was the most-discussed name on WallStreetBets. Risks: Susquehanna cut its target to $2.50, consensus is Hold, and the stock still trades below its 50-day ($2.95) and 200-day ($4.73) SMAs.
Business UiPath, Inc. (NYSE: PATH) is a New York-headquartered leader in enterprise automation and agentic business orchestration, offering robotic process automation (RPA), AI agents, process orchestration, process mining, document understanding, and test automation (Test Cloud). Founded in 2005 by CEO Daniel Dines and listed via IPO on April 21, 2021, it serves heavily regulated industries including financial services, healthcare, and pharma.
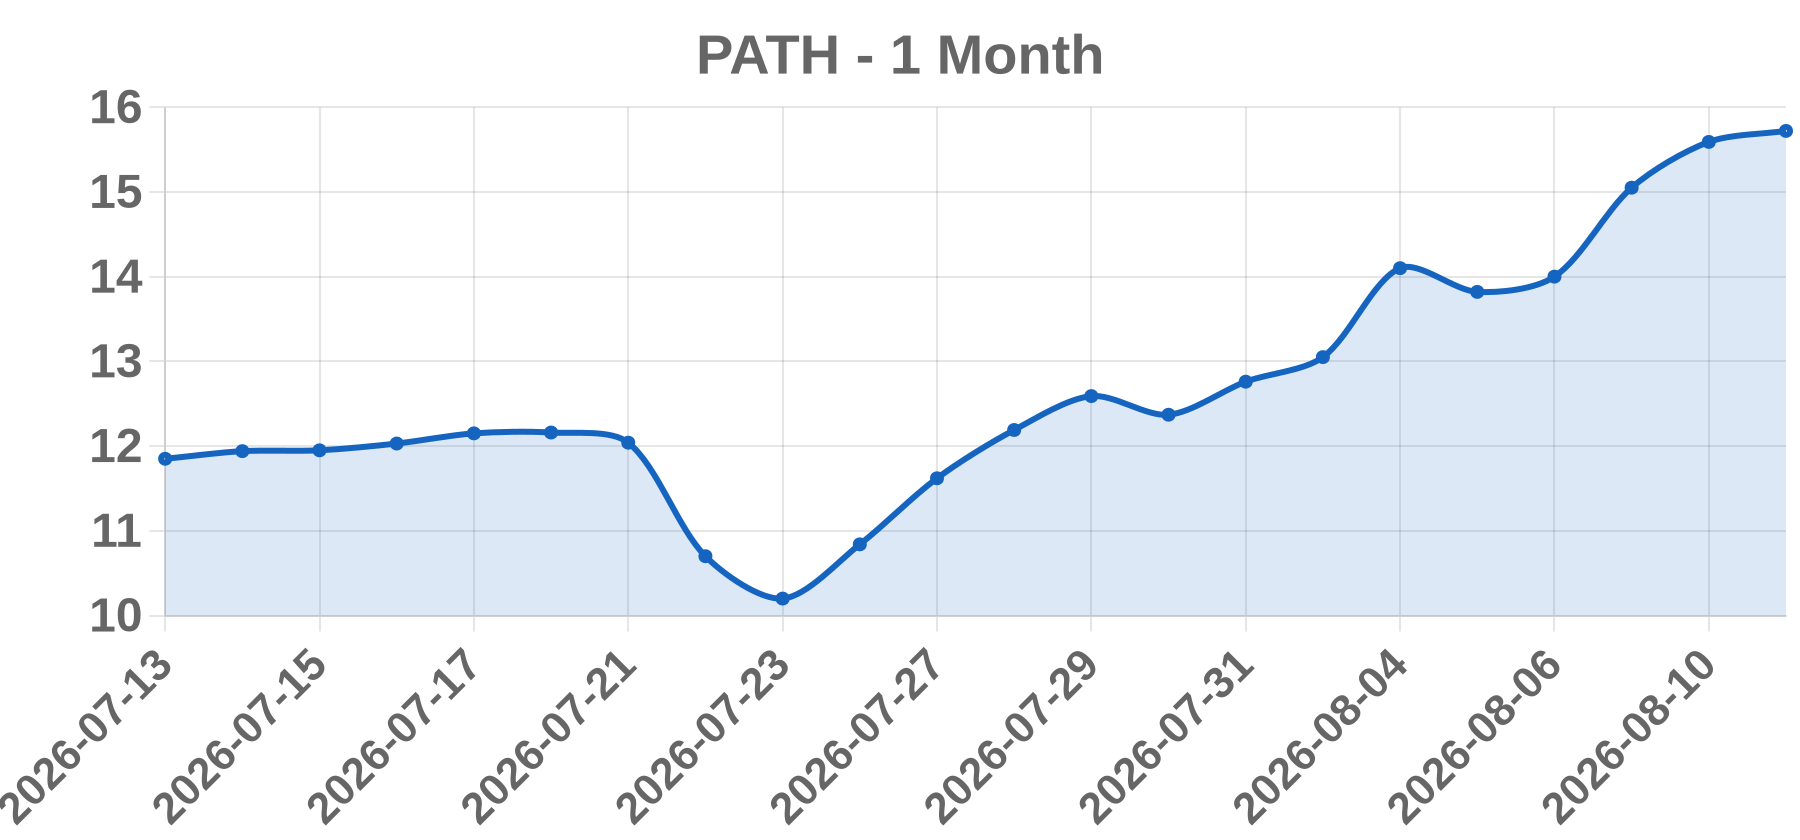
Today’s take UiPath fell 2.93% to $15.26 on Aug 12, 2026, after touching an intraday low of $14.98 (-4.7%), even though the S&P 500 (+0.3%) and Nasdaq (+0.7%) rose. No company-specific news drove the decline: next earnings are Sept 3, 2026, and the only recent item was the Aug 11 Merck KGaA (Darmstadt) win selecting UiPath Test Cloud. The tape shows sector rotation — the iShares Semiconductor ETF gained ~3.2% while the iShares Expanded Tech-Software ETF fell ~1% (Barron's) — as AI-trade money moved from software into chips. PATH had surged ~47% in three weeks (from ~$10.70 on July 22 to $15.72 on Aug 11) with RSI at ~71 vs. a $11.81 50-day MA, leaving it overbought and a natural profit-taking target after the OpenAI 'Presence' scare reversal. Very high short interest (~121.6M shares, ~30% of float per StockAnalysis) amplified the squeeze up; Aug 12 partially unwound it. Reports described traders 'locking in profits, particularly from the artificial-intelligence trade.'
Business Boxlight Corporation (Nasdaq: BOXL) is a Duluth, Georgia-based technology company that develops, sells, and services interactive technology solutions primarily for the global education market, with secondary sales to corporate, government, military, and healthcare sectors. Its award-winning brands include Clevertouch, FrontRow, and Mimio, spanning interactive flat-panel displays, LED video walls, classroom audio and campus-communication systems, collaboration software, and professional services.
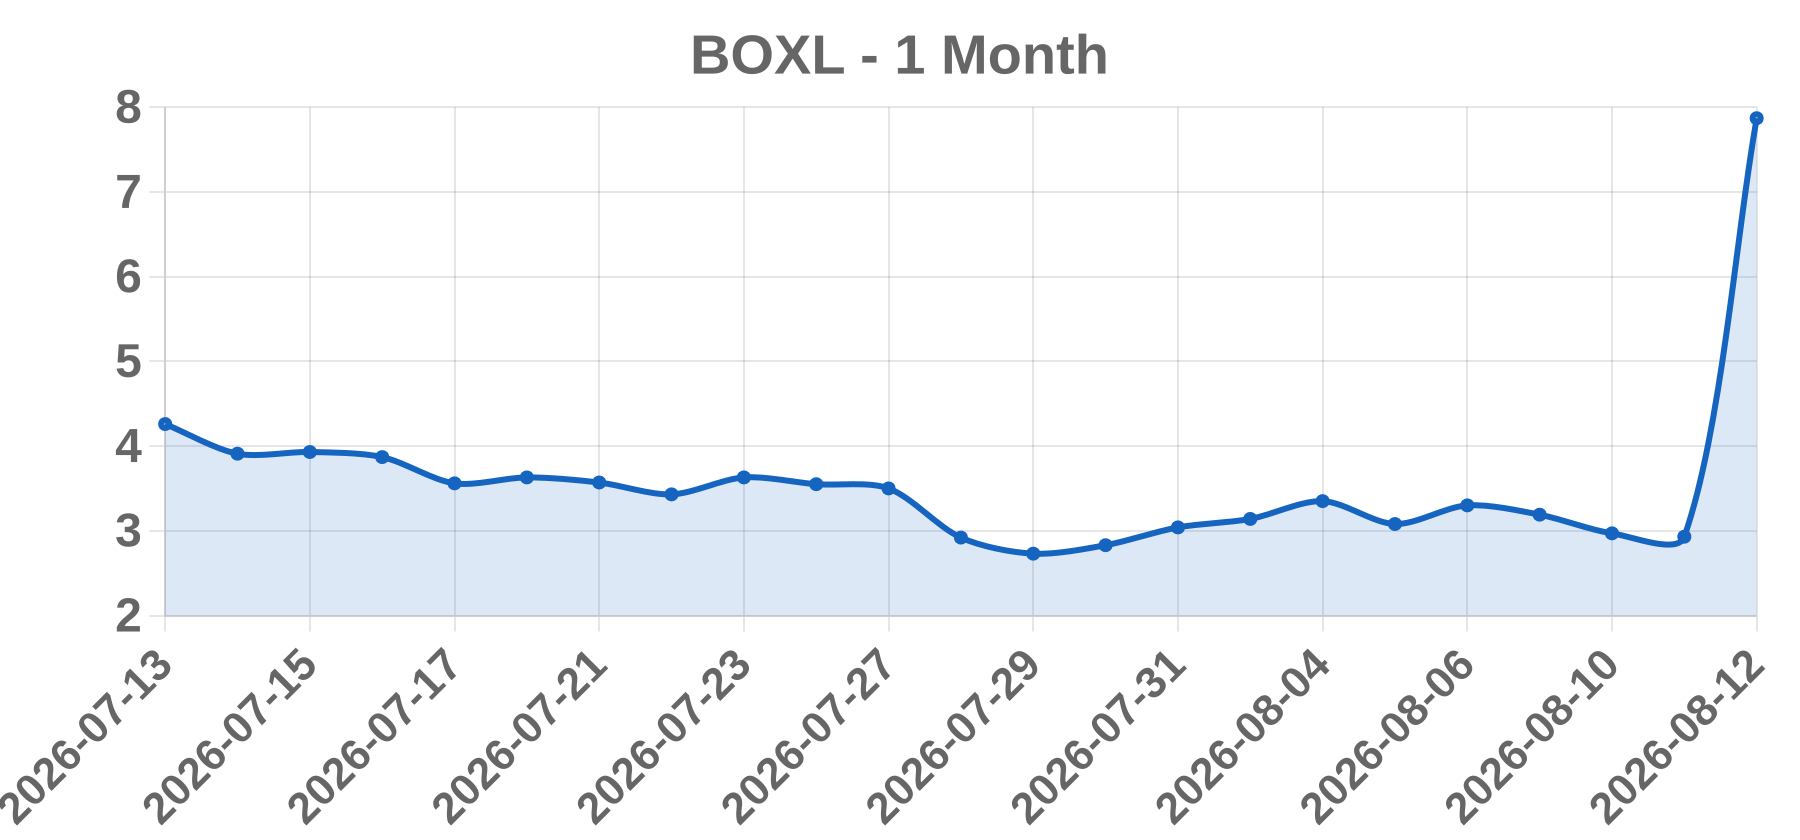
Today’s take Boxlight's +168.6% move was a two-stage news reaction. After the close on Aug 11, the company reported Q2 FY2026 revenue of $25.9M (-16% YoY, below ~$30.85M consensus) but swung to $0.5M net income vs a -$4.7M loss, with EPS of $0.34 vs -$55.00 a year earlier and a ~-$20 consensus; gross margin jumped to 49.8% from 35.0% aided by ~$2.8M in tariff refunds. It also completed an August 2026 equity raise of $4.8M net of fees, repaid $2.25M of WhiteHawk debt, and regained compliance with Nasdaq's minimum stockholders' equity requirement, removing a delisting overhang. Concurrently, it announced the initial closing of a $7.5M Series D Convertible Preferred PIPE ($5.5M funded; 937,500 shares at $8.00 purchase / $10.00 stated value, 20% OID) plus a $15M, 36-month equity line with Secure Net Capital LLC; a 4.99% beneficial-ownership cap limited near-term dilution. The stock jumped ~57% after hours to $4.62, then on Aug 12 it opened at $4.57, peaked at $9.89, and closed at $7.87, turning into a micro-cap short squeeze.
Business TEN Holdings, Inc. (Nasdaq: XHLD), headquartered in Langhorne, Pennsylvania, operates through its subsidiary Ten Events, Inc., an event technology company providing virtual, hybrid, and webinar platforms supported by production and managed services for enterprise customers. Its platform powers webinars, town halls, investor communications, and continuing-education programs. The company went public in February 2025 and executed a 1-for-15 reverse stock split in December 2025.
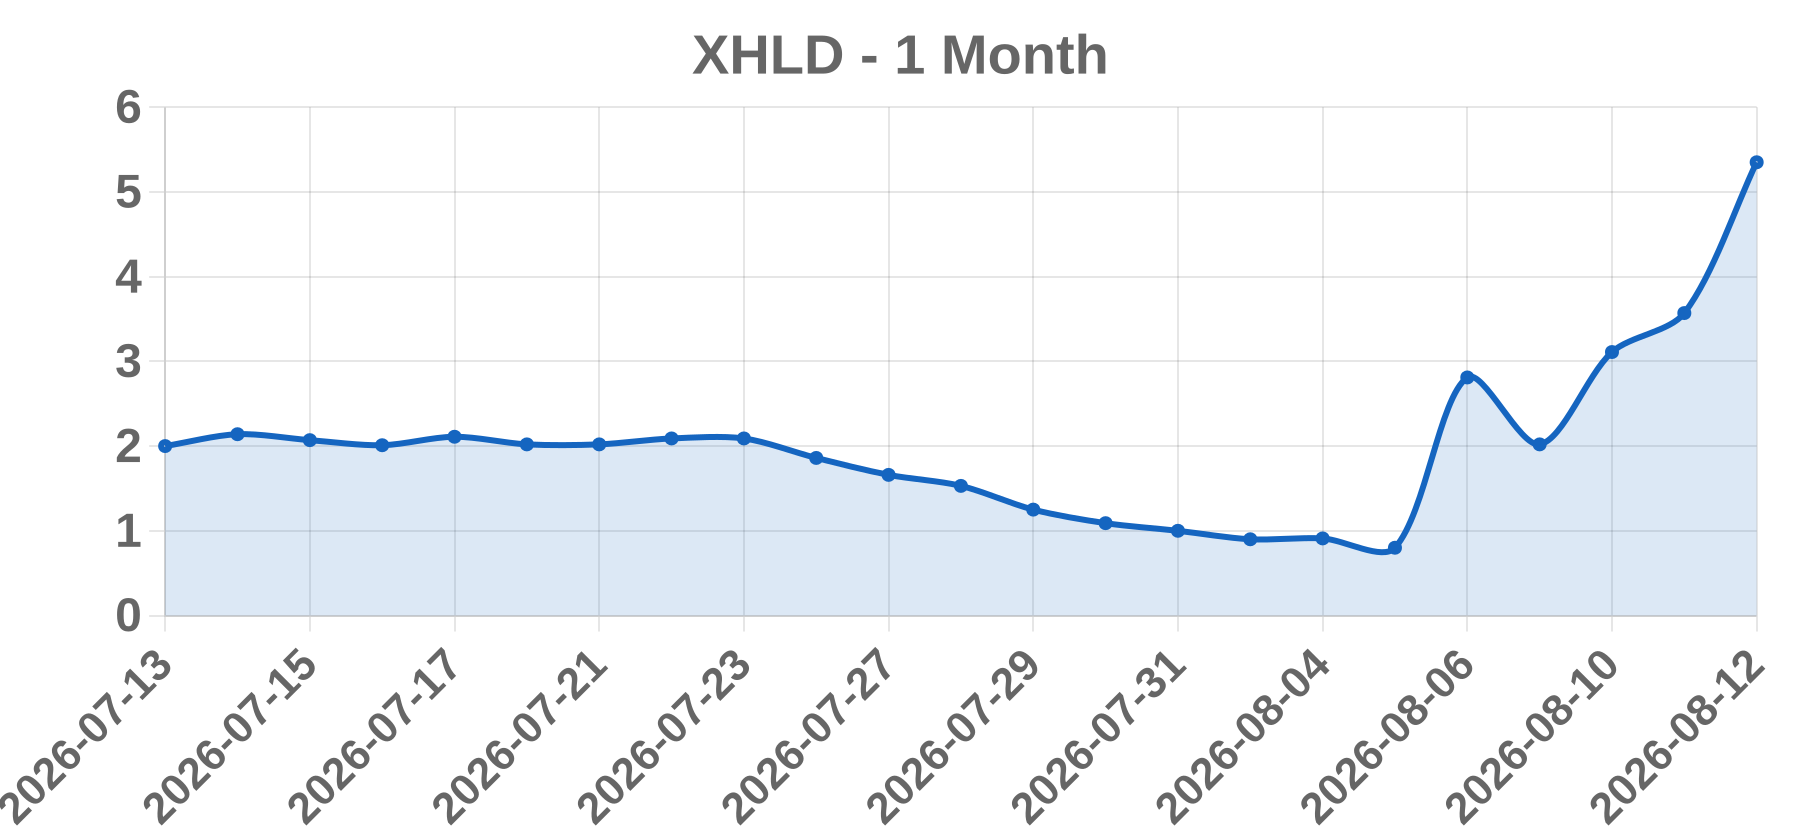
Today’s take XHLD surged 49.86% to close at $5.35 on Aug 12, 2026, after touching an intraday high of $6.26 (up ~75% from the $3.95 open) on 21.5M shares — roughly 2.7x its 20-day average of ~8.1M and more than twice its ~10.2M float. No new 8-K, press release, or guidance was issued that session; the move extended a post-earnings momentum run ignited by the Aug 10, 2026 Q2 release. Although Q2 revenue fell 34.5% to $731K with a net loss of $3.0M (-$0.70/share), CEO Virgilio Torres attributed the decline to revenue 'timing' and touted AI-driven analytics, the Webinar.net partnership, and a 'disciplined consolidation strategy' targeting acquisitions by December 2026. Short interest is negligible (43,835 shares; 0.37% of shares out), so this is long-driven retail momentum — with a dilution overhang from the June $7.5M offering at $1.00/share and an S-3 resale shelf — not a short squeeze. RSI ~77.6 flags overbought conditions.
Business CBL International Limited (Nasdaq: BANL) is a Cayman Islands-incorporated marine fuel logistics company and the listing vehicle of Banle Group, providing one-stop 'bunkering facilitation' services for vessel refueling across more than 70 ports in the Asia-Pacific region and beyond (including Malaysia, Hong Kong, China, Singapore, South Korea and Belgium). The company purchases marine fuel, including low-carbon and biofuel alternatives, and arranges physical delivery between ship operators and local physical suppliers, serving roughly 9 of the world's top 12 container liners.
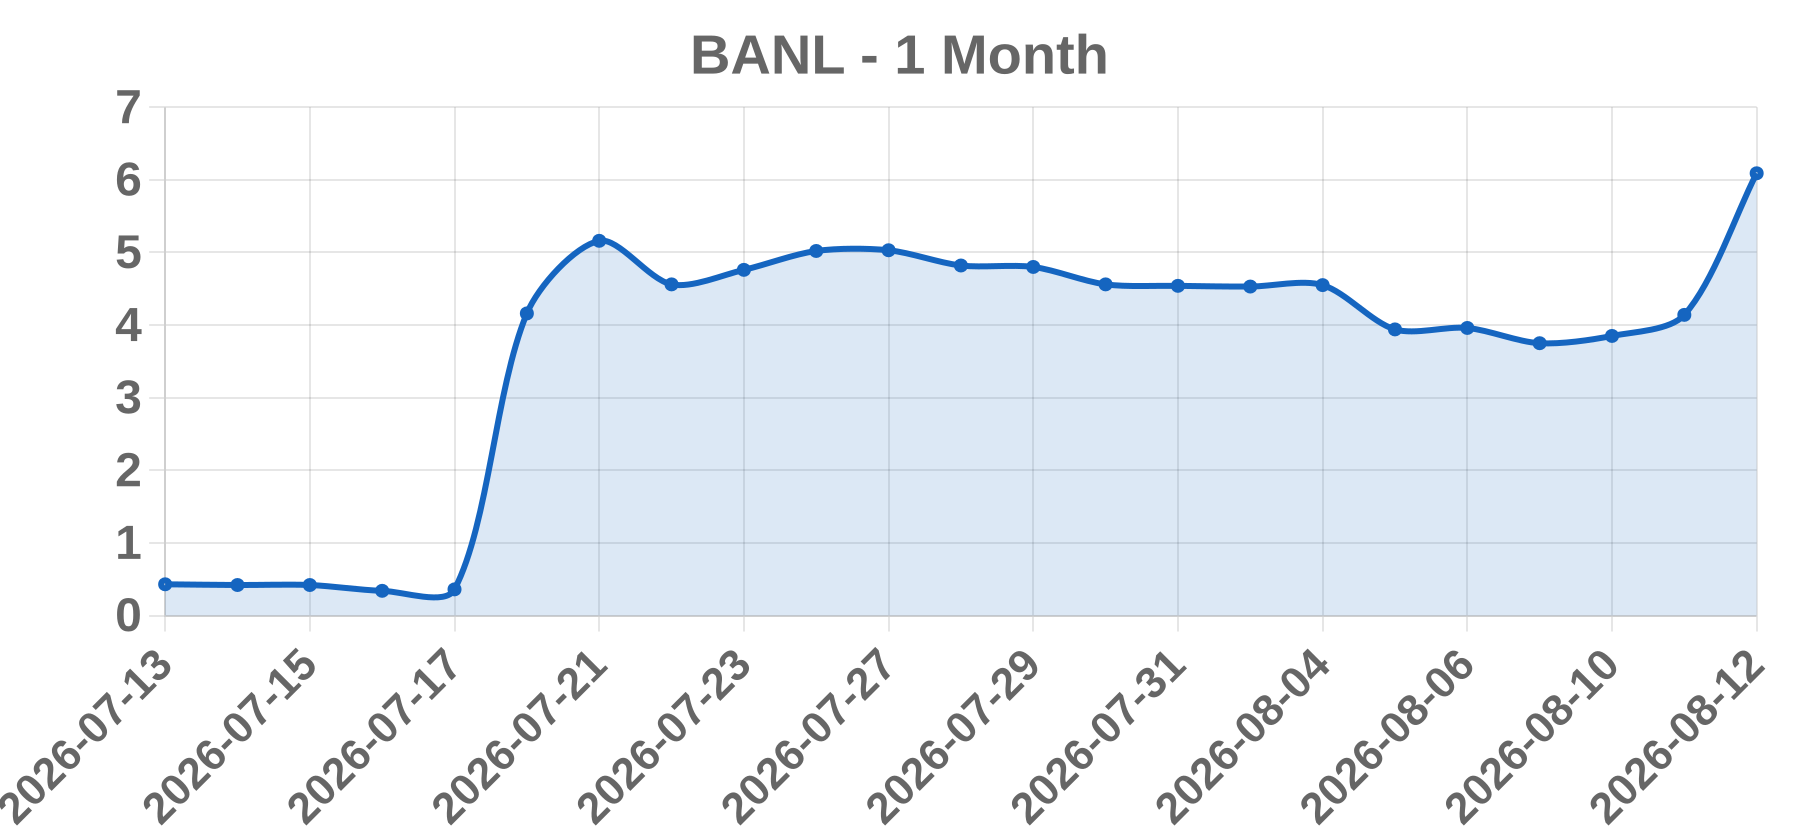
Today’s take BANL surged +47.28% to close at $6.09 on Aug 12, 2026, after swinging from an open of $4.05 to an intraday high of $7.50 (an ~85% peak-to-trough range) on ~2.9M shares — roughly 7x the ~407K public float and far above the ~10K-60K typical daily volume of prior sessions. Nasdaq's official halt log shows five consecutive LULD 'Volatility Pause' halts on BANL between 13:19 and 14:09 ET, the signature of a violent low-float squeeze. No company press release or fundamental disclosure accompanied the move; the most recent corporate news was Aug 4, when CBL announced Nasdaq confirmed it had regained $1 minimum-bid compliance after the July 20 1-for-13 reverse split cut the float to ~407K shares. Pre-session short interest was modest (~25.3K shares, ~6% of float as of Jul 15 settlement), though later readings show shorts ballooned to ~253K (~62% of float), indicating short covering plus fresh bearish positioning. The company previously issued an Oct 24, 2025 clarification stating it was not aware of any material undisclosed information behind similar volatility, underscoring a flow-driven, not news-driven, move.
Business Chaince Digital Holdings Inc. (Nasdaq: CD), formerly Mercurity Fintech Holding Inc., is a New York-based digital fintech company. Its three core business lines are blockchain and digital asset solutions, AI and HPC infrastructure (including liquid cooling for AI data centers), and financial services through Chaince Securities LLC, a FINRA-registered broker-dealer and RIA.
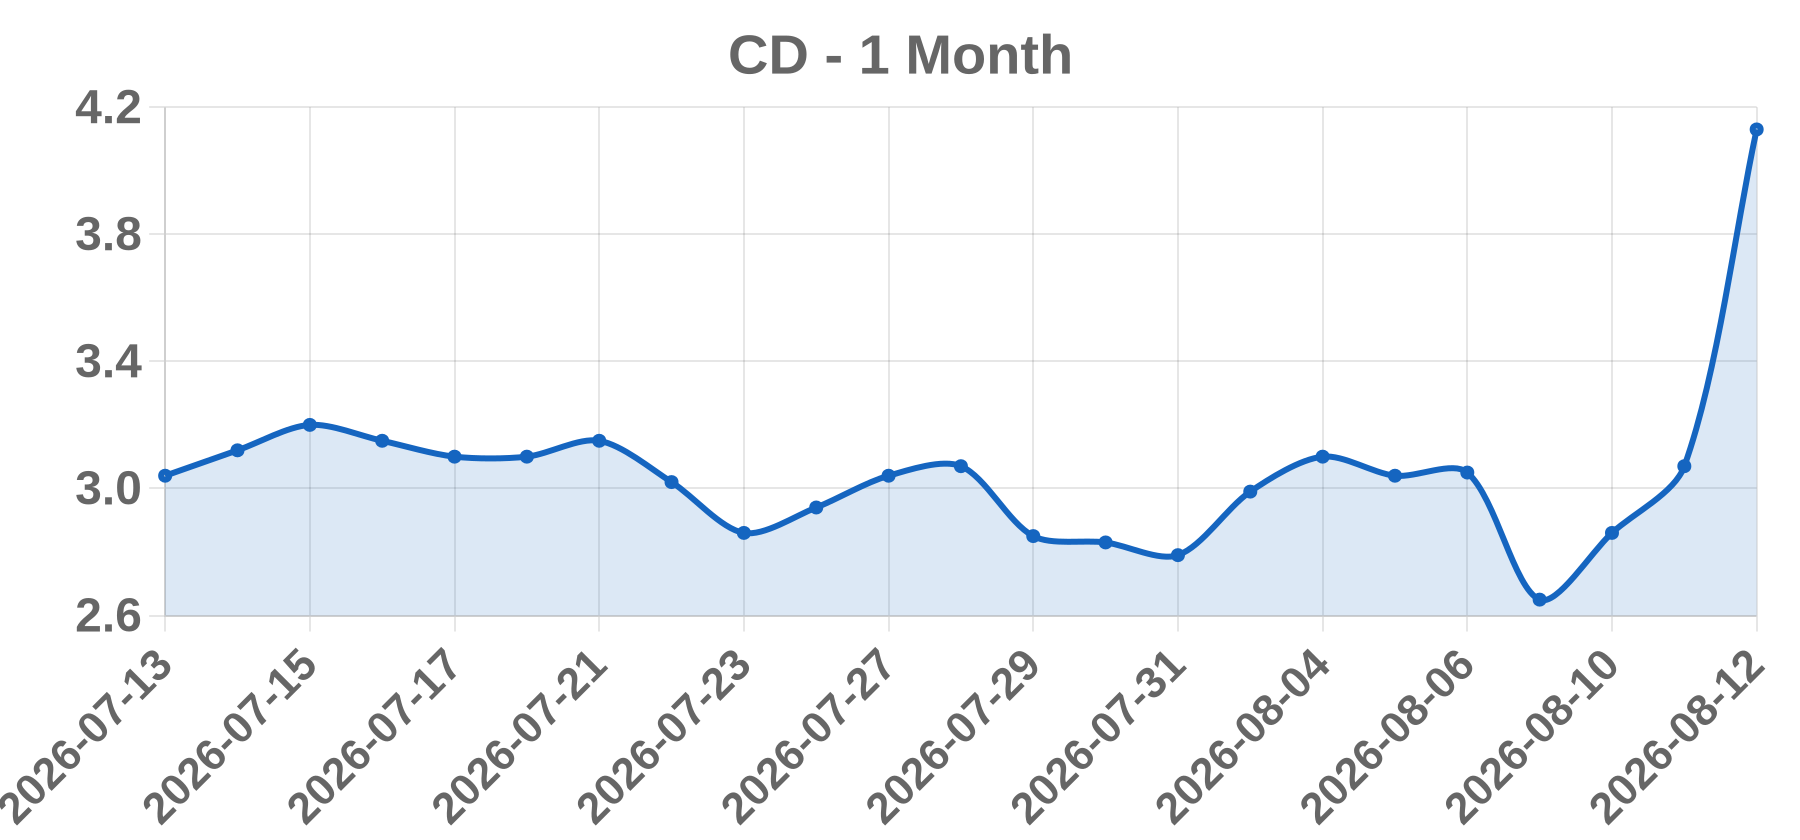
Today’s take Chaince Digital (Nasdaq: CD) surged 34.53% on August 12, 2026 to close at $4.13 after announcing a ~$16.2 million registered direct offering on August 10. The company sold 30.56 million ordinary shares at $0.53 each in a deal that closed on August 11, with proceeds earmarked for its digital asset reserve, working capital and general corporate purposes. Management framed the raise as strengthening the balance sheet and advancing digital asset management, real-world asset tokenization and its regulated capital markets platform — a narrative the market rewarded. After rising 7.92% on Aug 10 and 7.34% on Aug 11, shares added 34.53% on Aug 12 on volume of ~560,000 shares (about 4x the recent average), touching an intraday high of $4.28. The rally coincided with Bitcoin recovering above $64,000 ahead of July CPI, lifting crypto sentiment, while elevated short interest (~4.82M shares, ~26.9 days-to-cover per Yahoo Finance data as of 7/31/2026) likely amplified the move. CD still trades far below its $36.77 52-week high.
Business Nebius Group N.V. (NASDAQ: NBIS), formerly Yandex N.V., is an Amsterdam-headquartered AI cloud (neocloud) company building full-stack infrastructure — large-scale GPU clusters, its own data centers, cloud platforms, and developer tools — for AI developers and enterprises in the US, Europe, and beyond. The group also owns Avride (autonomous vehicles/delivery robots) and TripleTen (edtech) and holds equity stakes in ClickHouse and Toloka. Marquee customers include Microsoft and Meta under multi-billion-dollar, multi-year AI capacity agreements.
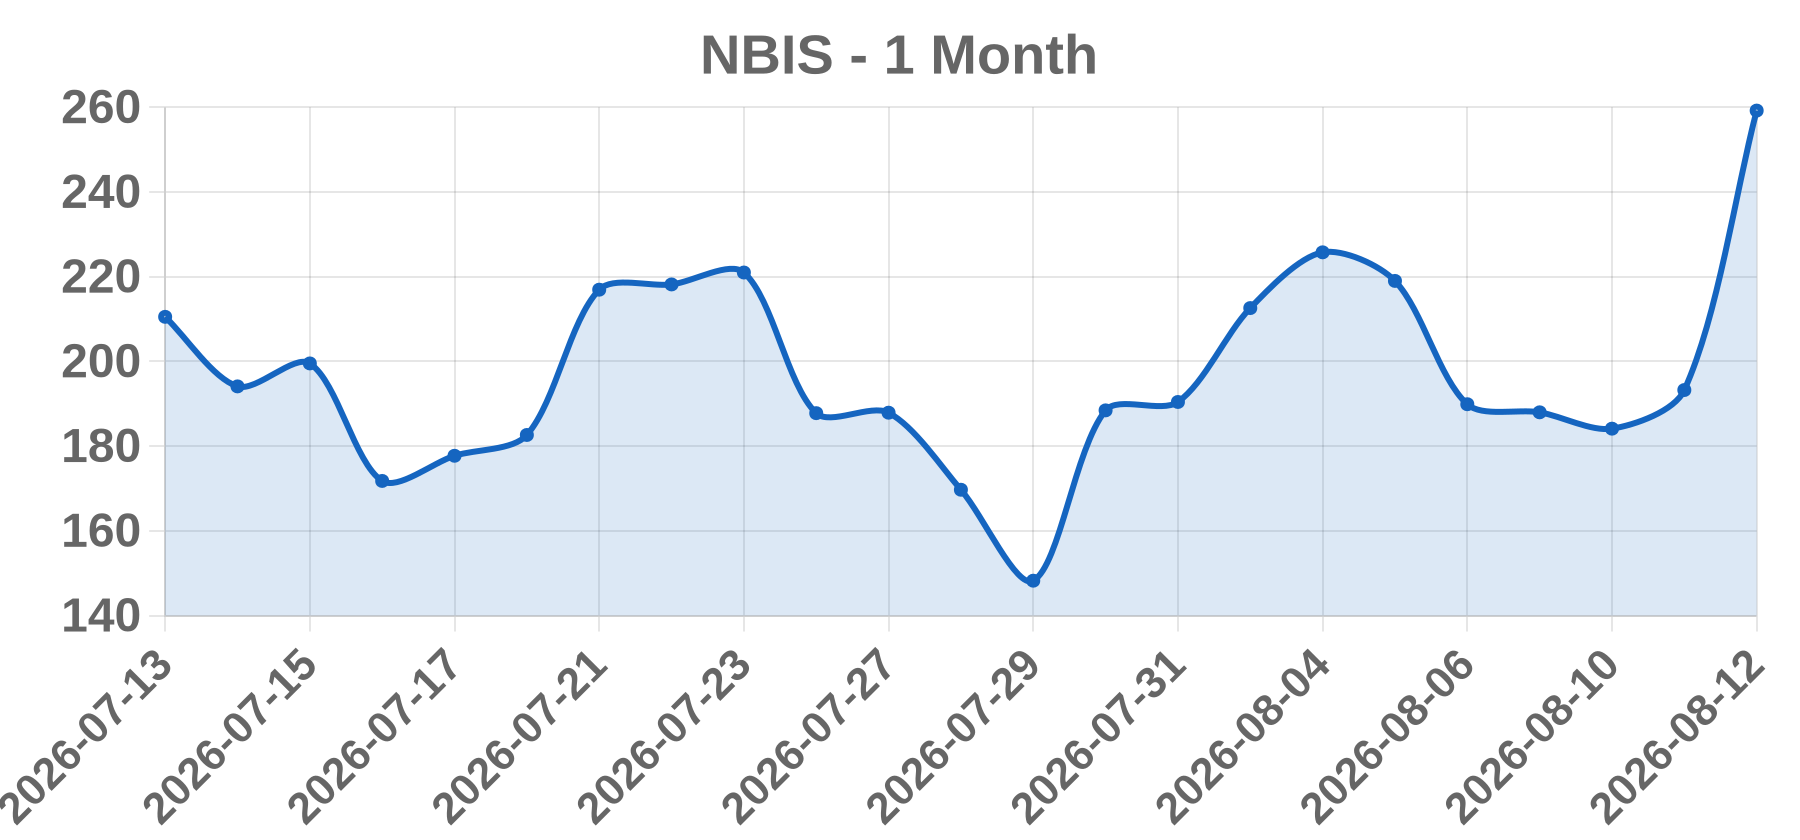
Today’s take NBIS surged 34.14% to $259.20 after reporting Q2 2026 results before Wednesday's open. Revenue of $582.3M (+454% YoY) beat consensus (~$572.7M), with AI cloud revenue up ~514% to ~$575M; adjusted EBITDA swung to +$236.2M from -$21.0M a year ago; adjusted net loss narrowed 64% to -$33.2M (EPS -$0.12 vs. -$0.62 consensus). Operating cash flow hit +$2,246M on customer prepayments, and management reaffirmed FY2026 revenue guidance of $3.0-3.4B with ~40% adjusted EBITDA margin, raised the year-end contracted-power target to 5 GW, and guided to >$9B of customer prepayments in 2026. CEO Arkady Volozh said 2027 capacity could effectively be sold out today. The outsized move was amplified by a squeeze setup — short interest ~28.8% of float and Michael Burry's disclosed $211.77 short — plus sector momentum from Nvidia's ~$500B neocloud financing initiative (Aug 10) and CoreWeave's strong Aug 11 results. Goldman Sachs reiterated Buy with a $286 target.
Business UTime Limited is a Cayman Islands exempted holding company headquartered in Shenzhen, China, operating its China businesses through a variable interest entity (VIE) structure; it listed on Nasdaq on April 6, 2021, under ticker WTO and switched to FXHO effective July 2, 2026, in preparation for its planned acquisition of Feixiaohao Technology. The company designs, develops, manufactures, sells and operates mobile phones, accessories and related consumer electronics, marketing two in-house brands (UTime, mid-to-high end; Do, value segment) and providing electronics manufacturing services (OEM/ODM) for third-party brands, with sales into India, Brazil, South Asia, Africa, Europe and the U.S. Following a 1-for-10 reverse split on June 22, 2026 and the July cancellation of unpaid placement shar
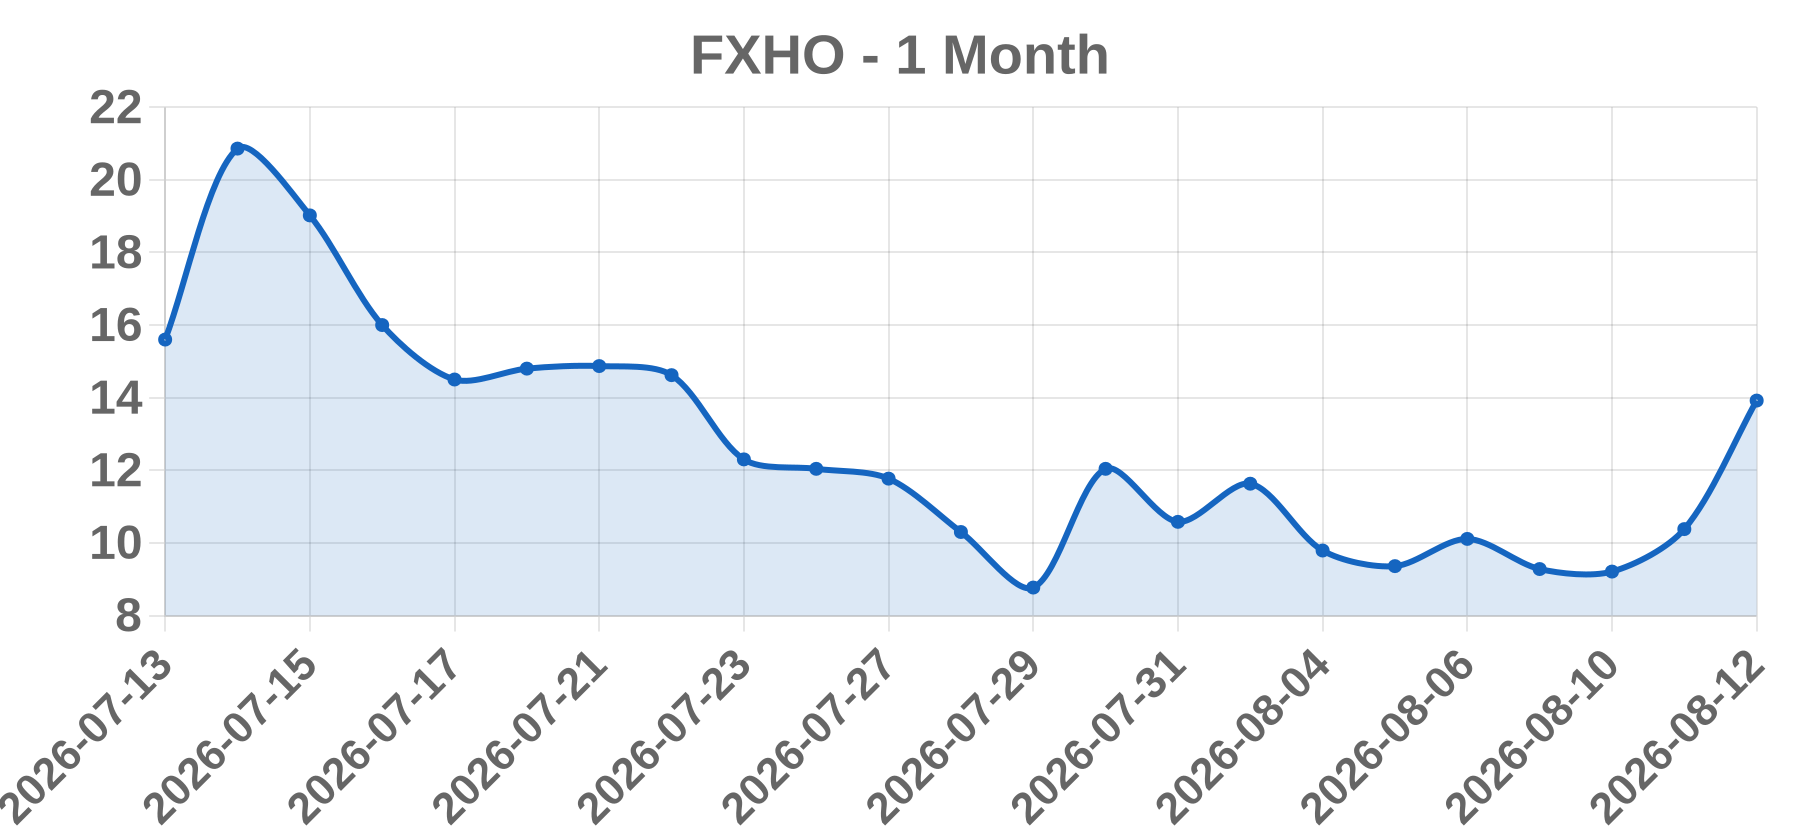
Today’s take UTime (FXHO) closed +34.10% at $13.92 on August 12, 2026, after trading between $9.45 and $14.14 (roughly 45% intraday amplitude) on ~1.02 million shares, marking a new two-week high, though it gave back 11%–21% after hours. No company-specific press release was dated August 12; the move is best read as an acceleration of the follow-through to the FY2026 annual results published August 10 (net loss narrowed ~96% YoY to RMB 27.84M). The stock closed slightly lower (-0.75%, $9.21) on the release day, then advanced +12.7% on August 11 and +34.1% on August 12 on roughly 7x the prior session's volume. The decisive amplifier is the share structure: after the June 22, 2026 1-for-10 reverse split and July share cancellations, the public float is extremely small (MarketWatch ~160K shares) while short interest of ~39.6K shares (settled 7/15/26) equated to ~24.8% of that float, leaving shorts exposed to forced covering as volume overwhelmed available supply — a pattern consistent with the July 6, 2026 spike (+171.5% on 8.1M shares) and the July 14, 2026 after-hours surge. Supporting narratives include insider alignment (180K restricted Class A shares granted to each of five directors in July)
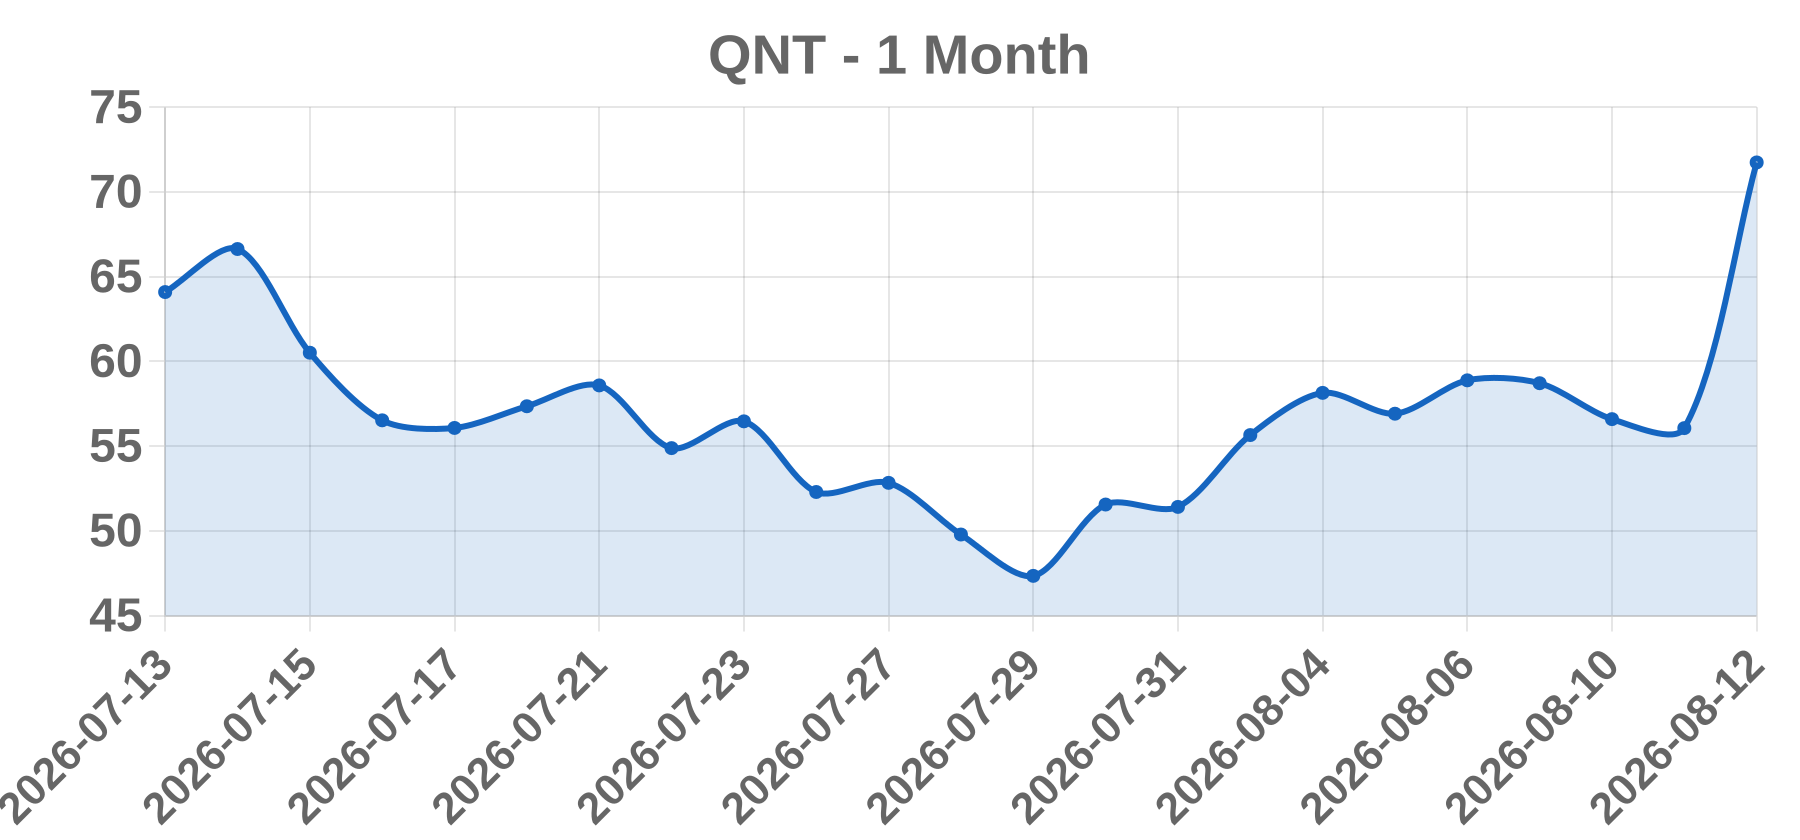
Business Quantinuum Inc. (Nasdaq: QNT) is a full-stack quantum computing company headquartered in Broomfield, Colorado, building trapped-ion quantum hardware (the 98-qubit Helios system on its QCCD architecture) and a software stack (Nexus platform, Guppy language). Formed in 2021 from Honeywell Quantum Solutions and Cambridge Quantum and backed by Honeywell, it completed the quantum sector's first traditional IPO on June 4, 2026 at $60/share, raising ~$1.68B.
Today’s take QNT's +27.97% surge to $71.74 was an earnings-gap-then-rally day after its first report as a public company (Aug 11, 2026). Q2 revenue rose 279% YoY to $8M, beating the ~$7.6M consensus, and management issued first formal FY2026 guidance of $28-32M (above street ~$26.5M), at least $120M in 2026 bookings, and >100% revenue growth in 2027. Co-announced was an industry-first Oracle partnership deploying Helios inside OCI, underpinning the bookings lift. Analysts reinforced the move: Bernstein raised its target to $95 (Outperform) and Rosenblatt reiterated Buy ($155) on Aug 12. With short interest of ~2.02M shares (~6.7% of float as of mid-July), the tape reflected short-covering plus institutional accumulation — the largest single-day percentage gain on record per Barron's/Dow Jones Market Data. Caveats: adjusted EPS of -$0.28 slightly missed the -$0.26 consensus, and GAAP net loss widened to $597M (mostly non-cash stock comp and warrant remeasurement).
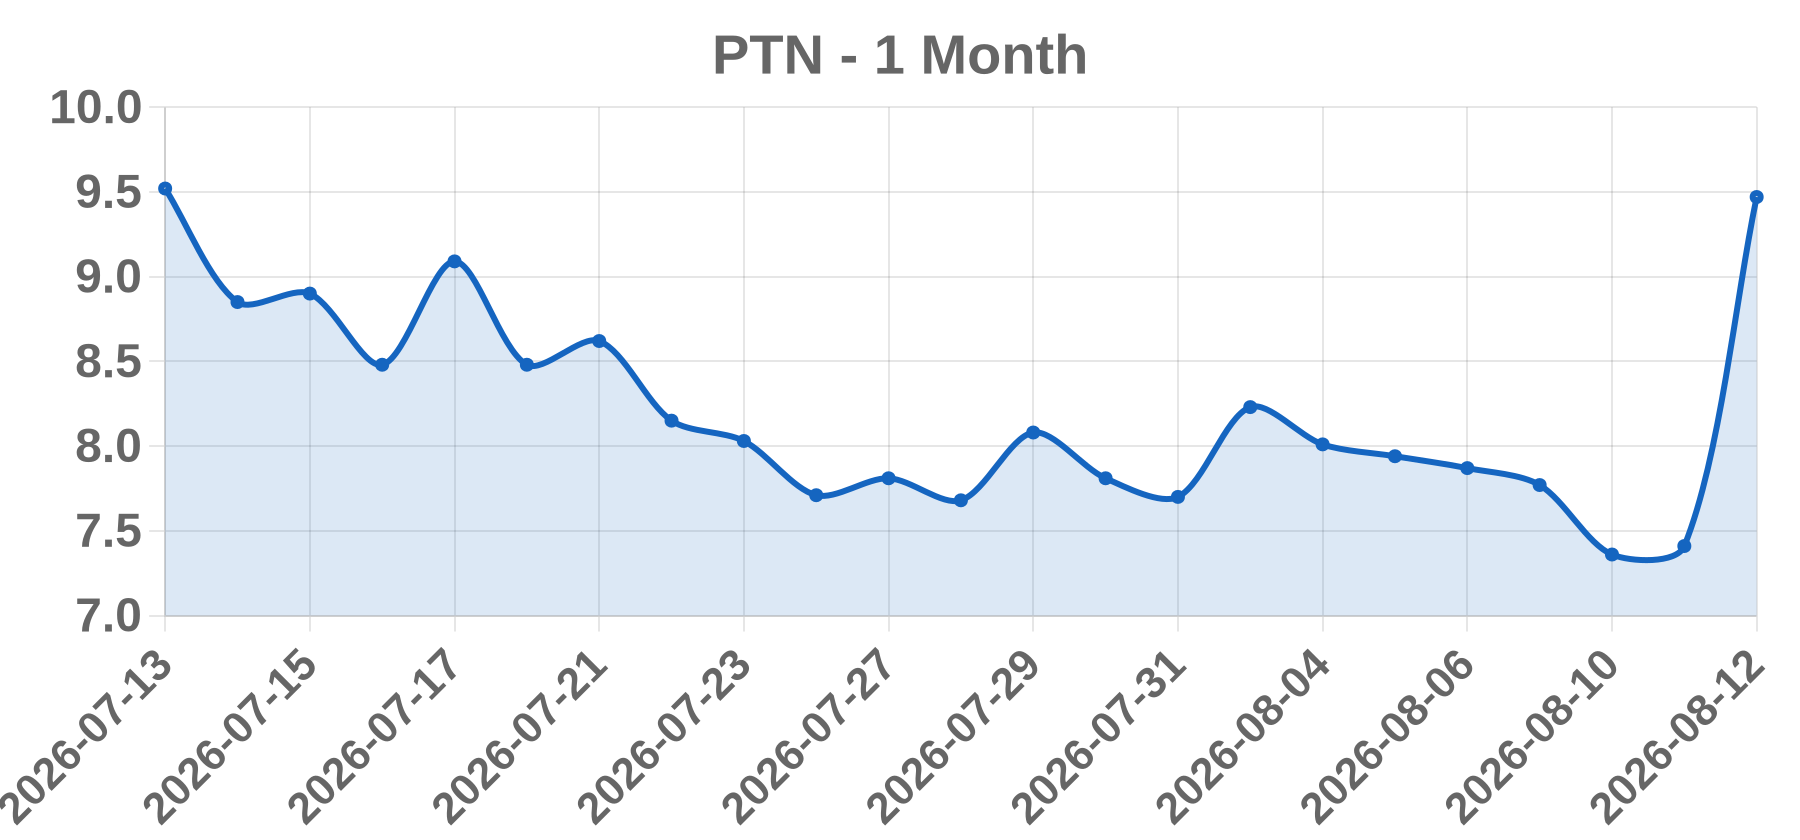
Business Palatin Technologies, Inc. (NASDAQ: PTN), based in Princeton, NJ, is a biopharmaceutical company developing first-in-class medicines that modulate the activity of the melanocortin receptor system. Its marketed product Vyleesi (bremelanotide) is the first FDA-approved melanocortin receptor agonist, indicated for acquired, generalized hypoactive sexual desire disorder (HSDD). The pipeline centers on MC4R agonists for rare obesity disorders (hypothalamic obesity, Prader-Willi syndrome, Bardet-Biedl syndrome), led by a once-weekly long-acting MC4R-selective peptide (IND targeted for Q4 2026) and next-generation oral small-molecule candidates (IND targeted for H1 2027); the earlier oral candidate PL7737 was discontinued over selectivity and dosing concerns. Other programs include bremelanotide
Today’s take On August 12, 2026, PTN surged +27.80% to close at $9.47 (intraday range $7.27-$9.58) on roughly 180K shares, about 17x its ~10K-share daily average, in a name with only ~1.6M float and ~19% of the float sold short (settlement date July 15, 2026: ~304K shares short, roughly 18 days to cover). No company-specific press release or 8-K was filed on the day; the stock gapped up at the open and ran to close near its high, classic squeeze price action. The trigger appears to be sector momentum: Neurocrine's ~$2.9B agreement to acquire Soleno (April 2026) and Vertex's ~$10B agreement to acquire Crinetics (July 2026) put a spotlight on rare-obesity/MC4R assets, and a StreetWatch/Newsfile feature (August 6, 2026) highlighted Palatin as a next-generation MC4R pure-play. Rhythm Pharmaceuticals' Q2 2026 results (August 3) showing IMCIVREE revenue of $71.3M further validated the MC4R commercial opportunity. After sliding from roughly $31 (early 2026) to $7.36 (August 10), PTN was a crowded-short, oversold micro-cap that snapped back violently. Three covering analysts rate the stock Strong Buy with a $53.50 average target, but the day's move lacked a company-specific fundamental catalyst; key ri
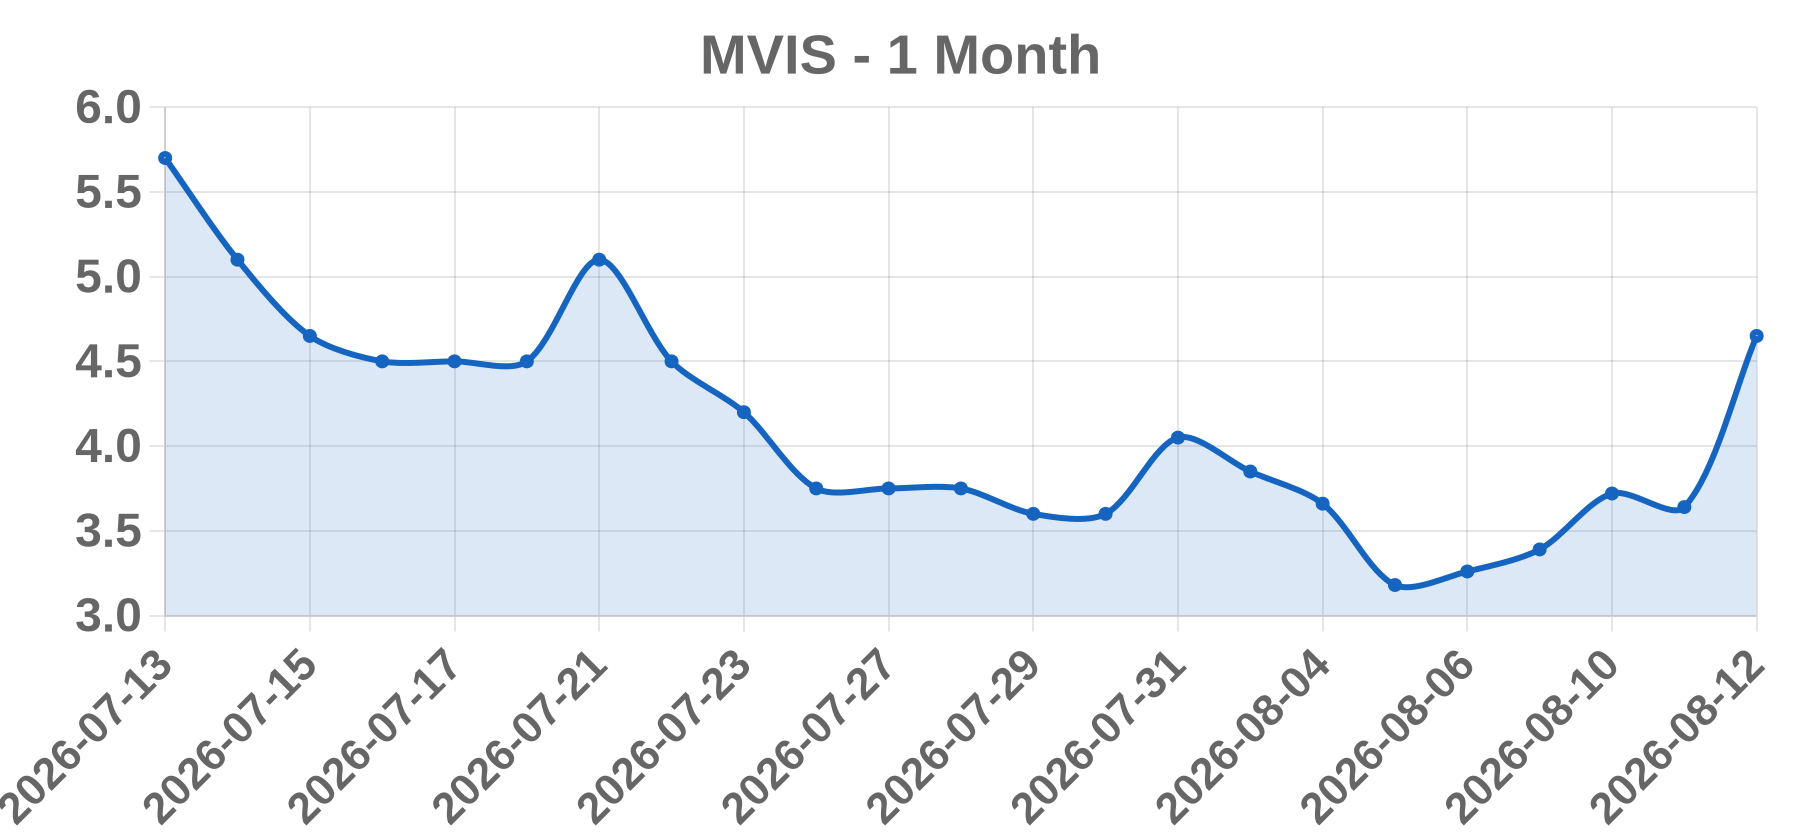
Business MicroVision, Inc. (MVIS) is a Redmond, WA-based developer and supplier of lidar sensors and perception software serving automotive, industrial automation, security & defense, robotics, and autonomous aerial markets. On August 5, 2026, the company launched the MOVIA Air product family (MOVIA Air and MOVIA Air Plus), lightweight airborne lidar solutions purpose-built for UAVs and autonomous aircraft, and announced a live demonstration of MOVIA Air Plus at the Navy-led Joint Interagency Field Experimentation (JIFX 26-4) held August 10-14 at Camp Roberts. On August 6, 2026, MicroVision reported Q2 2026 results, highlighted revenue growth, improved gross margins, the launch of MicroVision Semiconductor, a long-term IRIS lidar development agreement with a construction/mining equipment OEM, and l
Today’s take The +27.75% surge to $4.65 on August 12, 2026 (open $3.67, high $4.90, low $3.67; prior close $3.64) was driven by defense/drone narrative momentum around the ongoing JIFX 26-4 live demonstration of MOVIA Air Plus (Aug 10-14), amplified by a defense-media cycle including The Defense Post (Aug 7) and a NextGen Defense piece (Aug 11) spotlighting MicroVision's UAV lidar. The move was magnified by short-squeeze mechanics: after the 1-for-15 reverse split the float stood at only ~23.8M shares, short interest was ~3.5-4.0M shares (borrow fee ~25%, up ~14 points per TheFly/TipRanks early-August data), and volume expanded to ~1.84M shares (~2-3x the ~640-850K average). Note the 'trading halted, news pending' item at 19:50 EDT cited in TheFly was dated July 31, 2026 and was tied to the reverse stock split, not August 12; no 8-K or press release was filed on August 12-13, and after-hours on Aug 12 was roughly flat at ~$4.62-4.63. The rally is best characterized as an event-driven (defense demonstration) re-rating combined with a squeeze in a heavily-shorted, post-split small-cap.
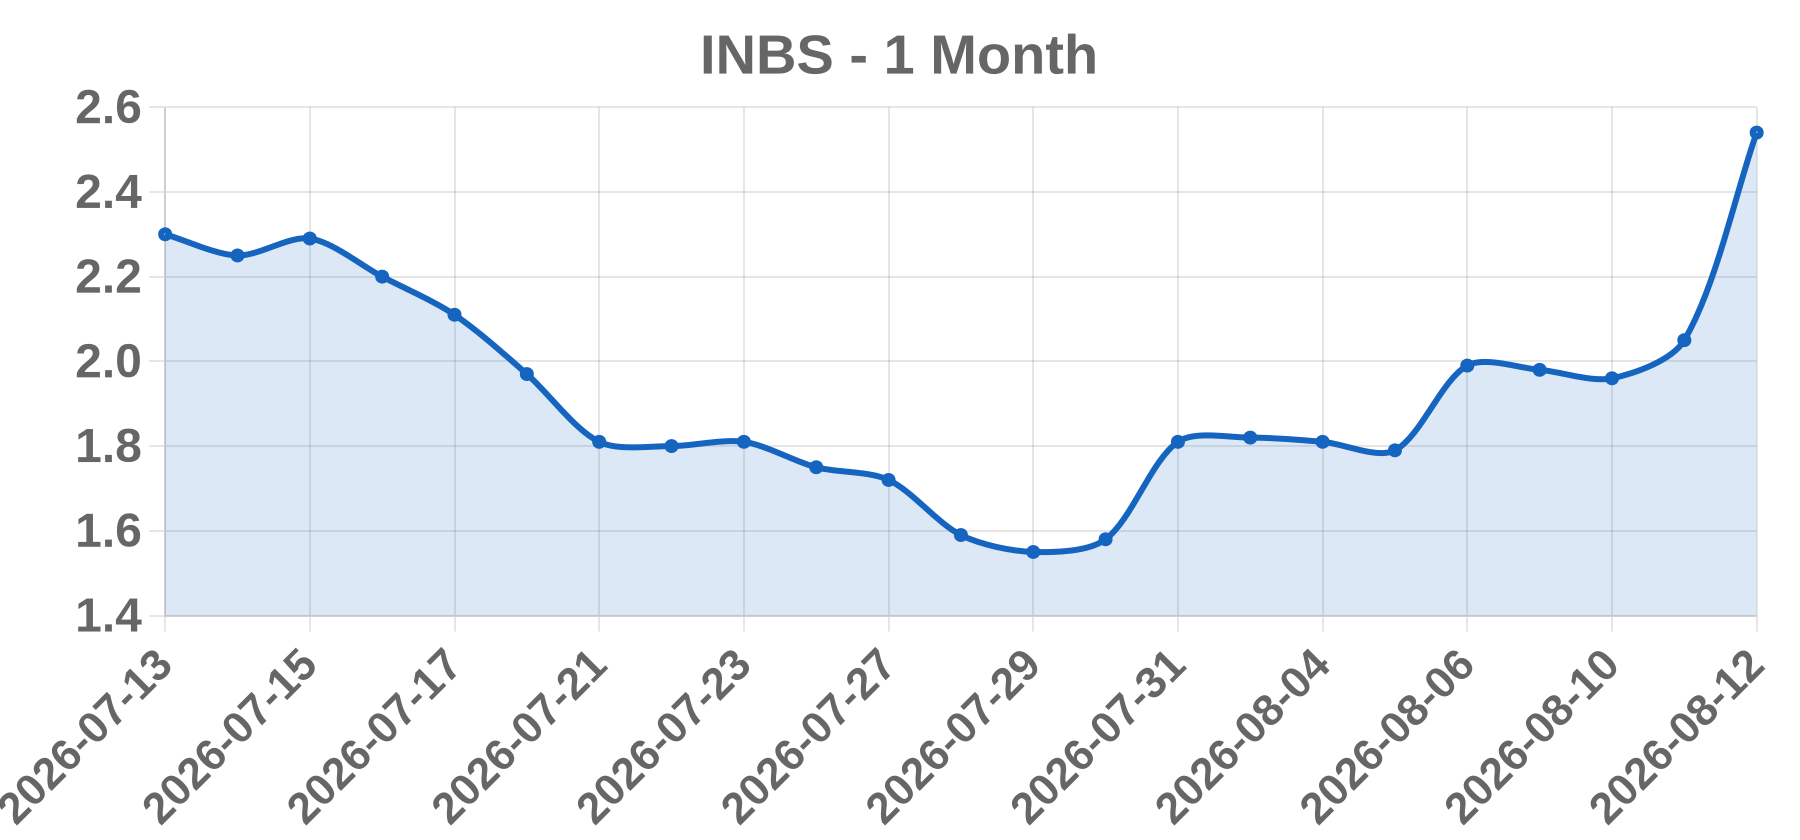
Business Intelligent Bio Solutions Inc. (Nasdaq: INBS), formerly GBS Inc., is a New York-based medical technology company focused on non-invasive, rapid testing. Its lead product, the Intelligent Fingerprinting Drug Screening System, analyzes fingerprint sweat to detect recent use of opiates, cocaine, methamphetamine and cannabis, with results in under 10 minutes. It is commercialized outside the U.S. and is pursuing FDA 510(k) clearance for codeine detection to enter the U.S. drug-screening market.
Today’s take The Aug 12 surge followed a regulatory milestone announced Aug 11: completion of the multi-site Method Comparison Study (135 participants across three U.S. sites, run with CenExel, administered by nine operators) — the final study in the FDA 510(k) clinical program for codeine detection. Management said all clinical data collection is complete, with the 510(k) package submission targeted for H2 2026. Reaction was delayed: shares rose only +4.6% to $2.05 on ~46K shares on release day, then accelerated Aug 12 — opening at $2.08, hitting a $2.59 high, closing at $2.54 (+23.90%) on 315,484 shares, roughly 7x the recent daily average and ~13% of the ~2.4M-share float. In a ~$6.1M market-cap microcap, this day-two follow-through produced an oversized percentage move. The catalyst was clinical/FDA progress, not earnings or M&A. Risks: the 510(k) is not yet submitted or cleared, the company is loss-making, and the stock remains ~80% below its 52-week high of $24.90.
Business Planet Green Holdings Corp. is a Nevada holding company headquartered in Flushing, New York, with operations conducted through subsidiaries in mainland China and Canada. It runs a diversified portfolio of consumer products (tea products such as cyan brick, black and green tea), chemical products, and online advertising services, and has recently added lactoferrin-based chewable immune tablets. It trades on NYSE American under the ticker PLAG.
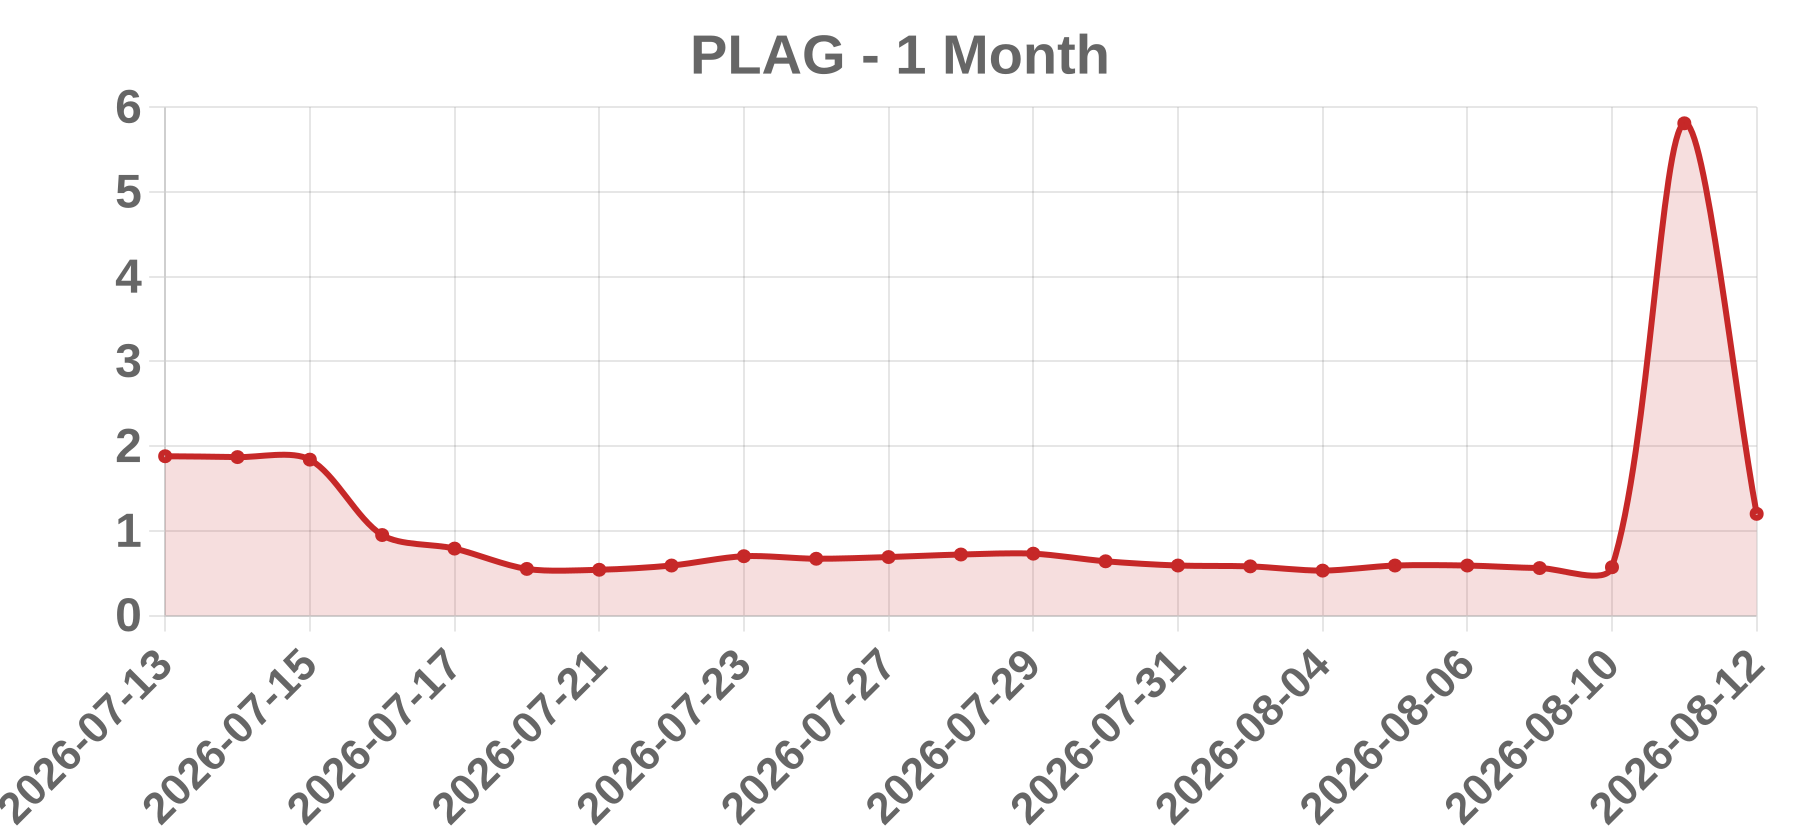
Today’s take PLAG collapsed 79.35% on Aug 12, 2026, closing at $1.20 after opening at $1.35 and printing a low of $1.12, with no new company-specific news that day. The crash was the violent unwinding of the prior session's +927% promotional spike: on Aug 11, a PRNewswire release announced commercial operations to source, market and distribute lactoferrin for China plus a planned Chief Scientist hire, driving the stock from $0.57 to a $6.81 intraday high and a $5.81 close on ~189M shares. With only ~14.2M shares outstanding, that session implied extreme float turnover and likely short covering, making Aug 12 a textbook pump-and-dump-style reversal as early buyers exited into thin support. Fundamentals never justified the run: Q1 2026 revenue ~$6.36M with ~18.4% gross margin, negative stockholders' equity near -$1.8M, payables over $9.4M, a May 2026 going-concern audit opinion, and an NYSE American compliance plan through June 2026.
Business Greenland Energy Company (NASDAQ: GLND) is a pre-revenue, exploration-stage oil and gas company headquartered in Denver, Colorado, focused on the ~2-million-acre Jameson Land Basin in East Greenland, where it plans the region's first modern onshore drilling campaign. It listed on Nasdaq in late March 2026 via a de-SPAC with Pelican Acquisition Corp. Under an earn-in with AIM-listed 80 Mile plc, GLND fully funds the drilling program to earn up to a 70% project interest; it has no production or proved reserves.
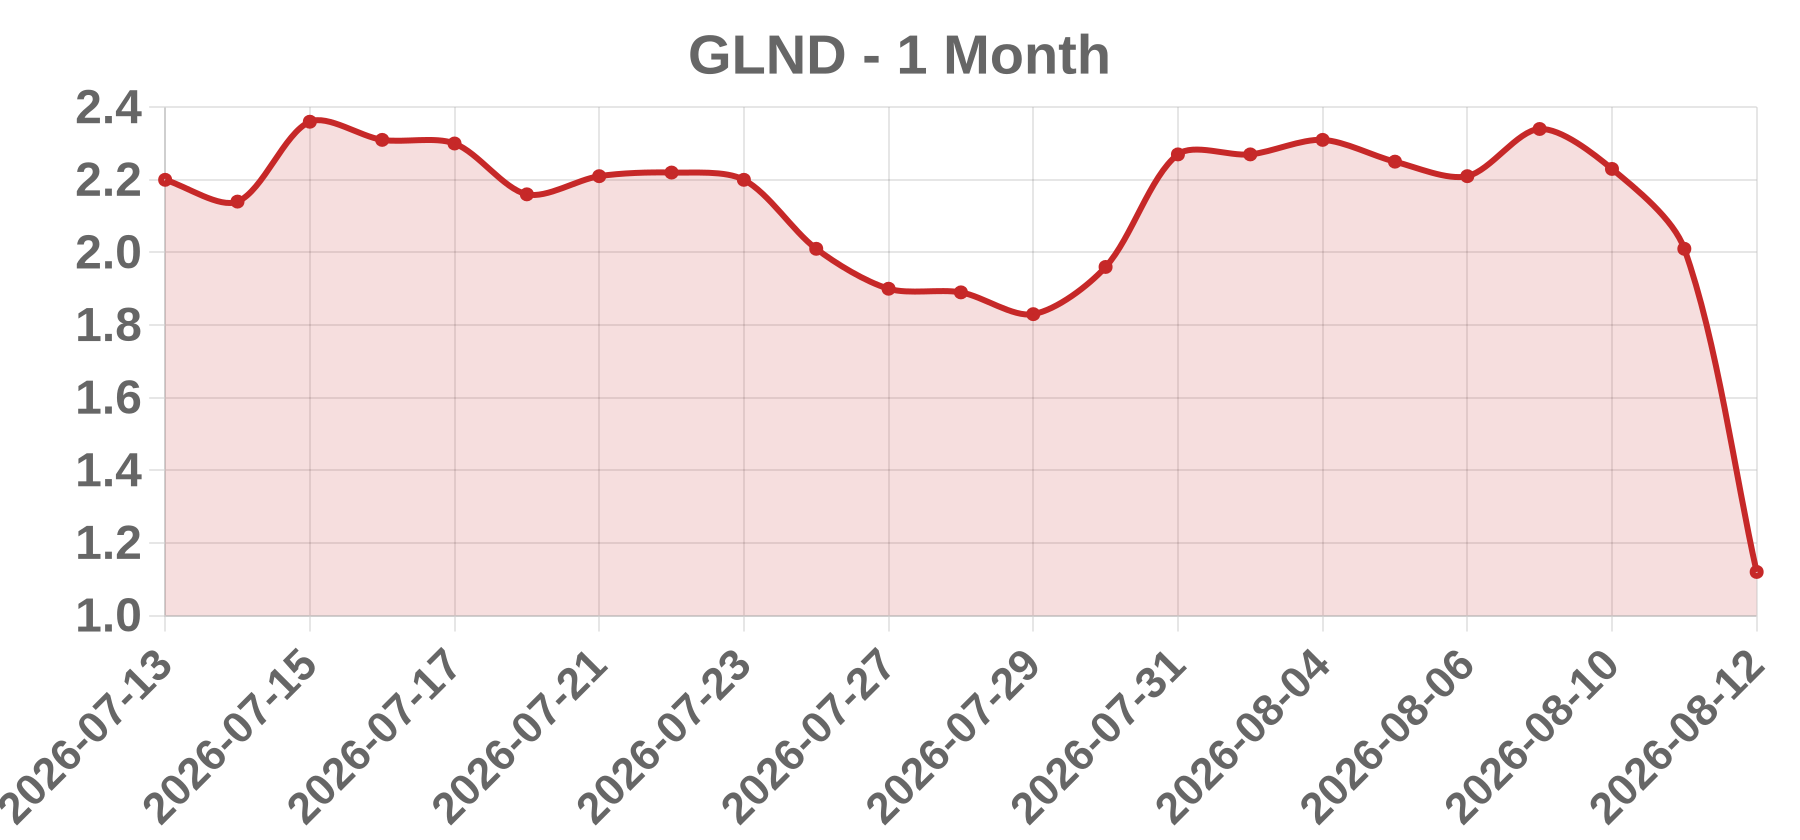
Today’s take GLND plunged 44.53% to close at $1.12 on Aug 12, 2026 (open $1.44, low $1.10) on ~13.7M shares, roughly 14-15x its ~0.9-1.0M average. The collapse followed a regulatory chain: on Aug 10, Greenland's Minister Múte B. Egede told KNR it was "not realistic" for the company to drill this autumn, contradicting GLND's public 2026 timetable, and the government issued a "strong warning" after an excavator and ~15 containers were landed at Nerlerit Inaat airport without approval. On Aug 11, GLND fell 9.87% to $2.01, then dropped another 18.91% to $1.63 in after-hours after its 6:25 PM ET press release confirmed a targeted permit timeline of winter 2027. The Aug 12 session repriced the stock as the near-term H2-2026 drilling catalyst — the core of its speculative value — was deferred roughly a year, while the three Jameson Land licences expire Dec 31, 2028, leaving little schedule cushion. Down ~95% from its $23 March-2026 listing high, GLND is now effectively an option on a winter-2027 permit outcome.
Business National CineMedia, Inc. (NASDAQ: NCMI), headquartered in Centennial, Colorado, is the largest cinema advertising platform in the U.S., operating through its wholly owned subsidiary NCM LLC. It sells on-screen advertising in the Noovie(R) pre-show program and digital out-of-home lobby advertising across approximately 22,000 theater and lobby screens in over 1,750 theaters spanning 183 DMAs, with exclusive network-affiliate exhibitors including AMC, Cinemark and Regal. The company emerged from Chapter 11 bankruptcy in 2023 and has roughly 93.7 million diluted shares outstanding.
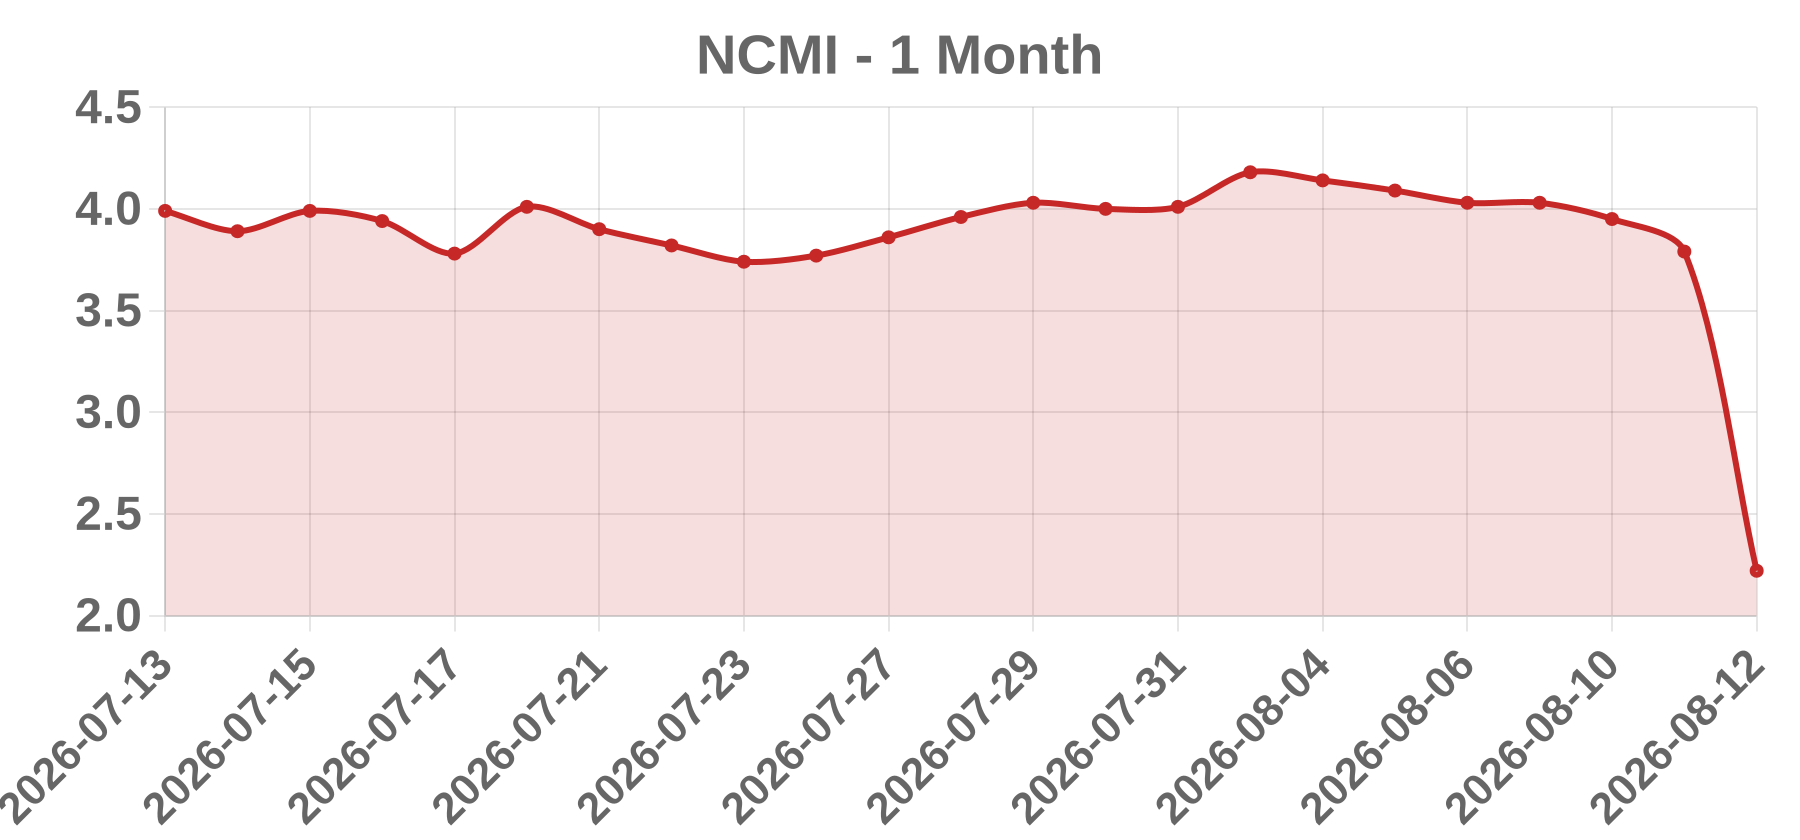
Today’s take After the close on Aug 11, 2026, NCMI reported Q2 2026 revenue of $58.4M (+12.7% YoY vs. $51.8M), a GAAP net loss of $9.9M (-$0.11/share), and Adjusted OIBDA of ~$2.1M — missing consensus (est. -$0.09 EPS on ~$59.3M revenue) and landing at the low end of company guidance. Simultaneously, NCMI agreed to acquire Captivate Holdings for $275M (~10x pro forma EBITDA), funded entirely with new committed term debt, lifting net leverage to ~3.9x, and paused its dividend and share repurchases, while withholding forward guidance pending the deal. Shares fell ~15.6% to $3.20 in after-hours. On Aug 12, the stock opened at $2.61, traded $2.82–$2.16, and closed at $2.22 (-41.42%) on 10.5M shares (~25–40x the ~250–400K daily norm), near its low, while a benign July CPI (+0.1% m/m) and a rising S&P 500 confirmed the drop was company-specific. Wedbush cut its target $6.00→$5.00 and Barrington $5.00→$4.25, both maintaining Buy.
Business WF International Limited is a Cayman Islands holding company headquartered in Chengdu, China, listed on the Nasdaq Capital Market under WXM. Through its subsidiaries, it provides supply, installation, fitting-out, and maintenance services for HVAC, floor-heating, and water-purification systems, primarily for large commercial projects in China. Following a 10-for-1 reverse stock split effective June 4, 2026, the company has roughly 1.13 million shares outstanding and an ultra-thin float (~577K shares).
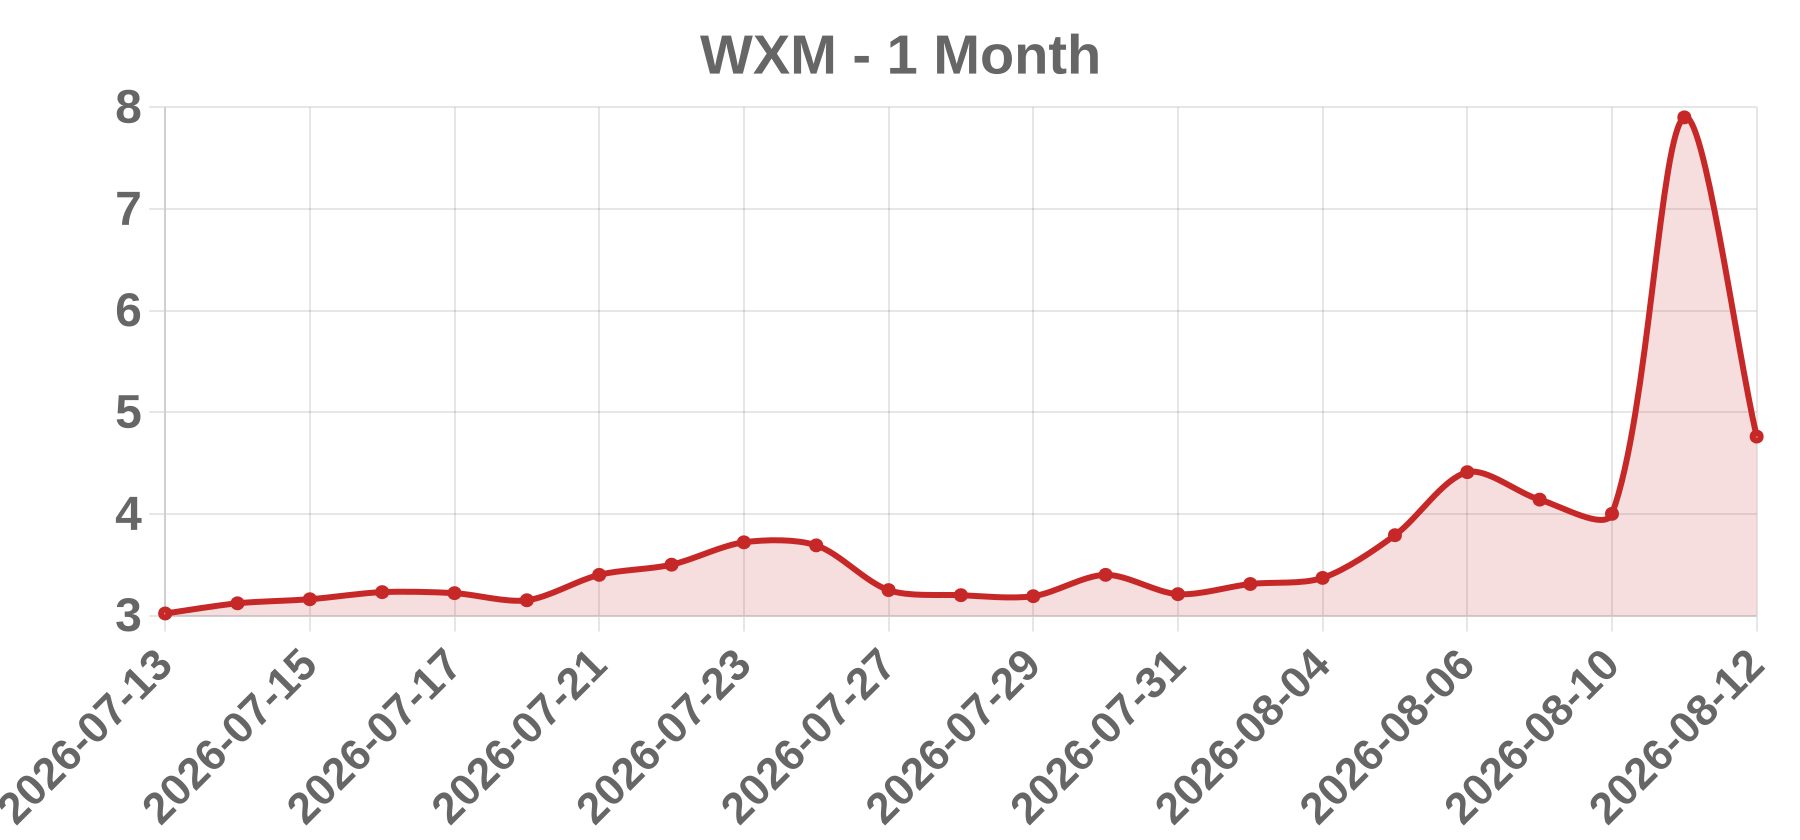
Today’s take WXM plunged 39.75% to $4.76 on Aug 12, 2026, unwinding the prior session's parabolic +97.5% surge to $7.90 (intraday high $12.80) on ~41.9M shares — versus typical daily volume of tens of thousands. The Aug 11 spike followed a weak earnings 6-K filed Aug 10 after the close: 1H FY26 (six months ended Mar 31, 2026) revenue fell 73.4% Y/Y to $2.33M with GAAP EPS of -$2.90; the quarter ended Mar 31 showed ~$1.2M revenue and diluted EPS of -$1.45. Investing.com found no identifiable fundamental catalyst for the surge, attributing it to speculative momentum in an ultra-low-float micro-cap (share count cut to ~1.13M by the June 4 reverse split). On Aug 12 there was no company news or SEC filing (EDGAR shows no 6-K/8-K on Aug 11 or Aug 12); WXM opened down 36% at $5.07, traded $4.12-$5.23, and closed at $4.76 on ~617K shares, drifting to $4.52 after hours. The session reflects classic profit-taking/mean-reversion as day-one chasers exited, with the stock still up ~19% versus the Aug 10 close of $4.00.
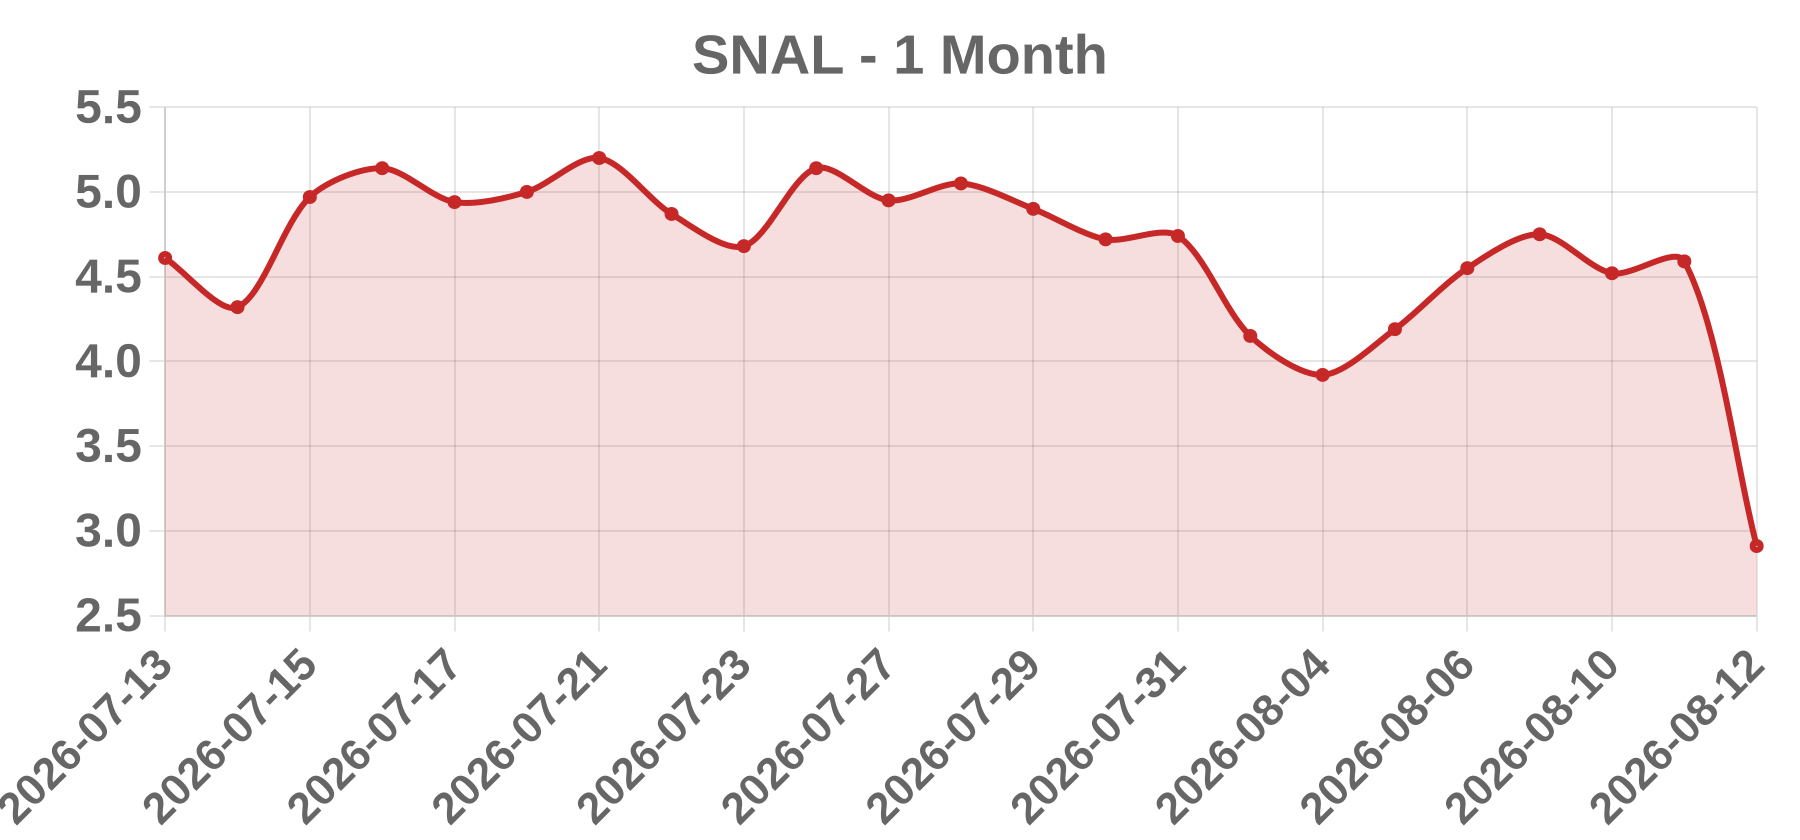
Business Snail, Inc. (Nasdaq: SNAL) is an independent developer and publisher of interactive digital entertainment for PC, console, and mobile, headquartered in Culver City, California. Its flagship franchise is ARK (Survival Evolved, Survival Ascended, Ultimate Mobile Edition), with a pipeline spanning Bellwright, indie titles, and upcoming AAA games such as For The Stars and 9 Yin Sutra: Immortal. The company listed on Nasdaq in November 2022 and operates as a subsidiary of Olive Wood Global Development Limited.
Today’s take Snail reported Q2 2026 results after the Aug 11 close that badly missed consensus: net revenue of $19.7M was down 11.3% YoY from $22.2M versus roughly $29M analyst estimates, and GAAP EPS of -$0.36 versus the ~$0.31 Zacks consensus. Bookings fell 19.6% YoY to $21.8M and units sold slipped to 2.0M from 2.1M. Management had guided for YoY growth partly on recognizing ~$11M of deferred revenue tied to ARK: Genesis Part 1 Ascended within Q2, but that DLC, along with Tides of Fortune and Dragontopia, launched in July, pushing recognition into Q3 and breaking the growth narrative. The net loss narrowed to $3.0M from $16.6M only because the prior year carried a $14M tax provision, while EBITDA widened to a -$3.0M loss. The stock fell ~30.7% after-hours to $3.18, then closed Aug 12 at $2.91 (-36.6%) on ~685K shares versus ~200-265K typical, near the low end of its post-split range and above the $1.70 52-week low. S&P 500 and Nasdaq were roughly flat, confirming a company-specific event; Noble Capital reiterated Outperform but failed to stem selling.
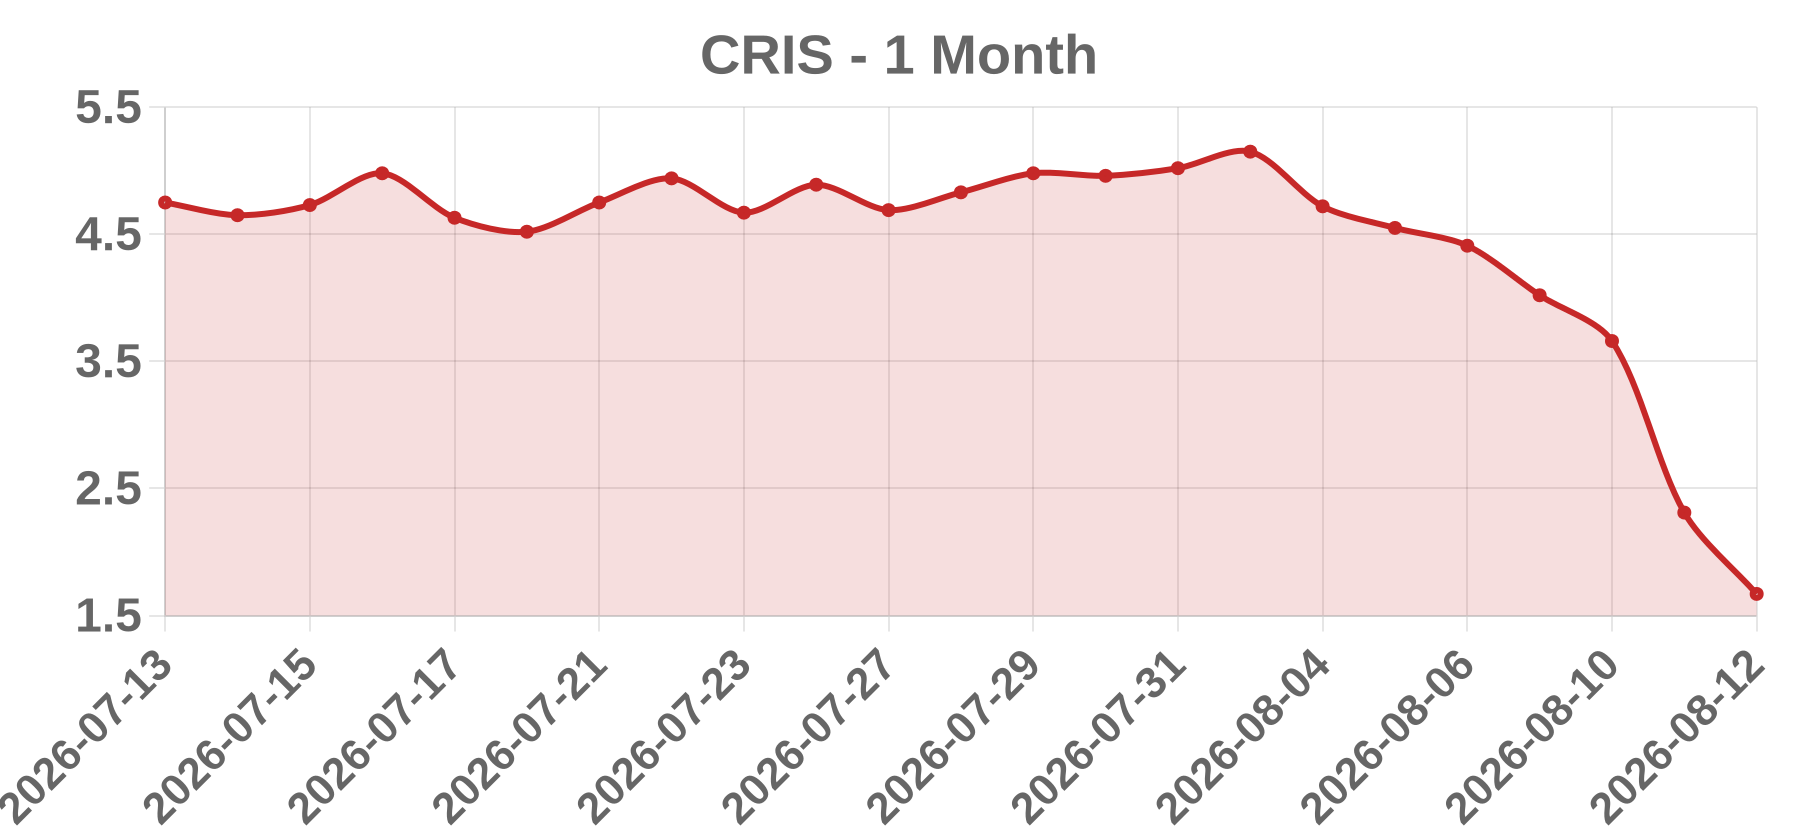
Business Curis, Inc. (NASDAQ: CRIS) is a clinical-stage biotechnology company based in Lexington, Massachusetts, focused on discovering and developing drug candidates for cancer treatment. Its lead candidate, emavusertib (CA-4948), is an oral small-molecule IRAK4 kinase inhibitor in development for primary CNS lymphoma (PCNSL), acute myeloid leukemia (AML), myelodysplastic syndromes (MDS), and chronic lymphocytic leukemia (CLL).
Today’s take Curis filed an S-1 with the SEC on Aug 10, 2026 to sell up to 3.73M common shares, up to 3.73M pre-funded warrants, and up to 3.73M August 2026 Warrants (5-yr term, $4.02 exercise price) in a best-efforts offering at an assumed $4.02 combined price, estimating ~$13.6M in net proceeds, with A.G.P. and Laidlaw as placement agents. With only ~1.95M shares outstanding, the potential ~7.46M registered shares could roughly double the float, driving severe dilution fears. On Aug 12, CRIS plunged -27.71% to $1.67, hitting a 52-week low of $1.63 intraday, cutting market cap to ~$3.25M on volume of ~1.15M shares versus a ~188K daily average. The drop compounds pressure from the 1-for-20 reverse split effective July 2, 2026, the Nasdaq compliance watch, and the Series-B warrant exercise window triggered by the July 30 CLL dosing milestone. Fundamentally, Q1 2026 net loss was $24.2M with $15.0M cash; offsetting positives include H.C. Wainwright's July 24 PT raise to $43 and 100% ORR in BTKi-naive PCNSL patients.
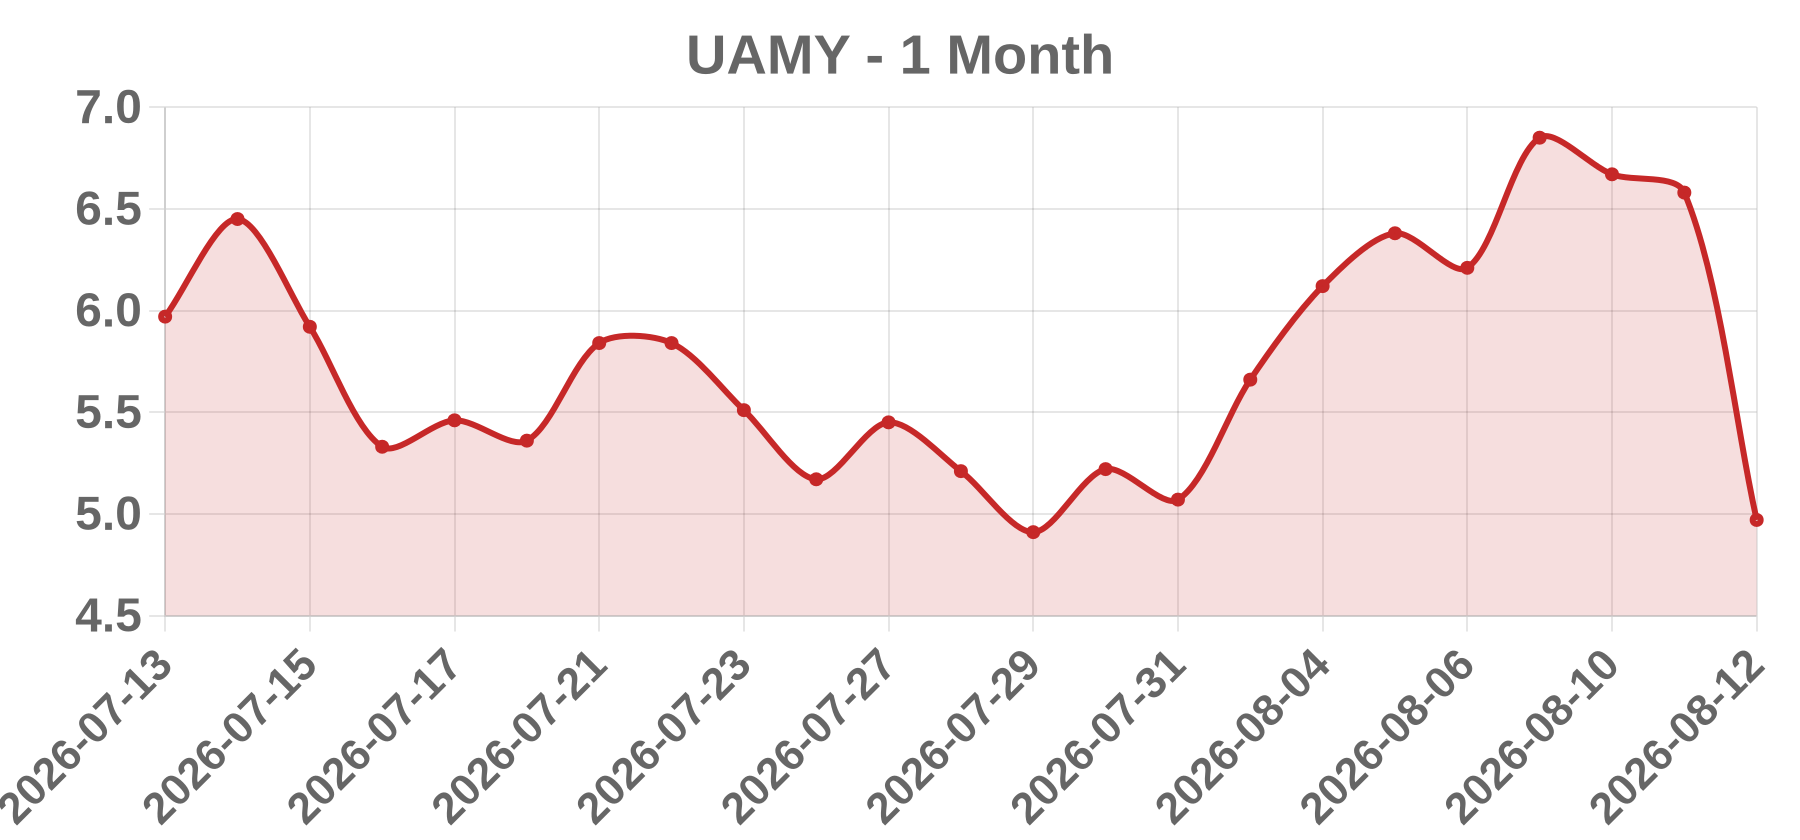
Business United States Antimony Corporation (NYSE: UAMY) is a Dallas, Texas-based critical-minerals producer and the only fully integrated antimony company outside China and Russia, operating North America's only two antimony smelters (Thompson Falls, Montana and Madero, Mexico). It produces antimony metal and antimony trioxide plus zeolite products from its Bear River Zeolite facility in Idaho, split into two reportable segments: Antimony and Zeolite. The company also holds a large US Defense Logistics Agency (DLA) antimony supply contract.
Today’s take UAMY reported Q2 2026 results after the Aug 11 close and the market repriced the stock on Aug 12. Revenue of $7.93M came in roughly 63% below the ~$21.7M consensus and down ~25% YoY despite antimony volumes rising 26% to 428,425 lbs, because realized antimony prices collapsed 52% to $13.70/lb and gross margin compressed from 27% to 7%. EPS of -$0.02 missed by $0.03. The decisive blow was FY2026 revenue guidance slashed to $60-75M from $125M (vs ~$115M consensus), confirming the H2 ramp was unachievable with spot prices near $10/lb. Net income of $0.1M stayed positive only because of a $6.8M unrealized gain on the Larvotto Resources stake, masking a ~$7.0M operating loss. Same-session, H.C. Wainwright cut its price target to $9.25 from $11.75 (Buy maintained). The stock closed -24.47% at $4.97, its biggest one-day drop since October 2025.
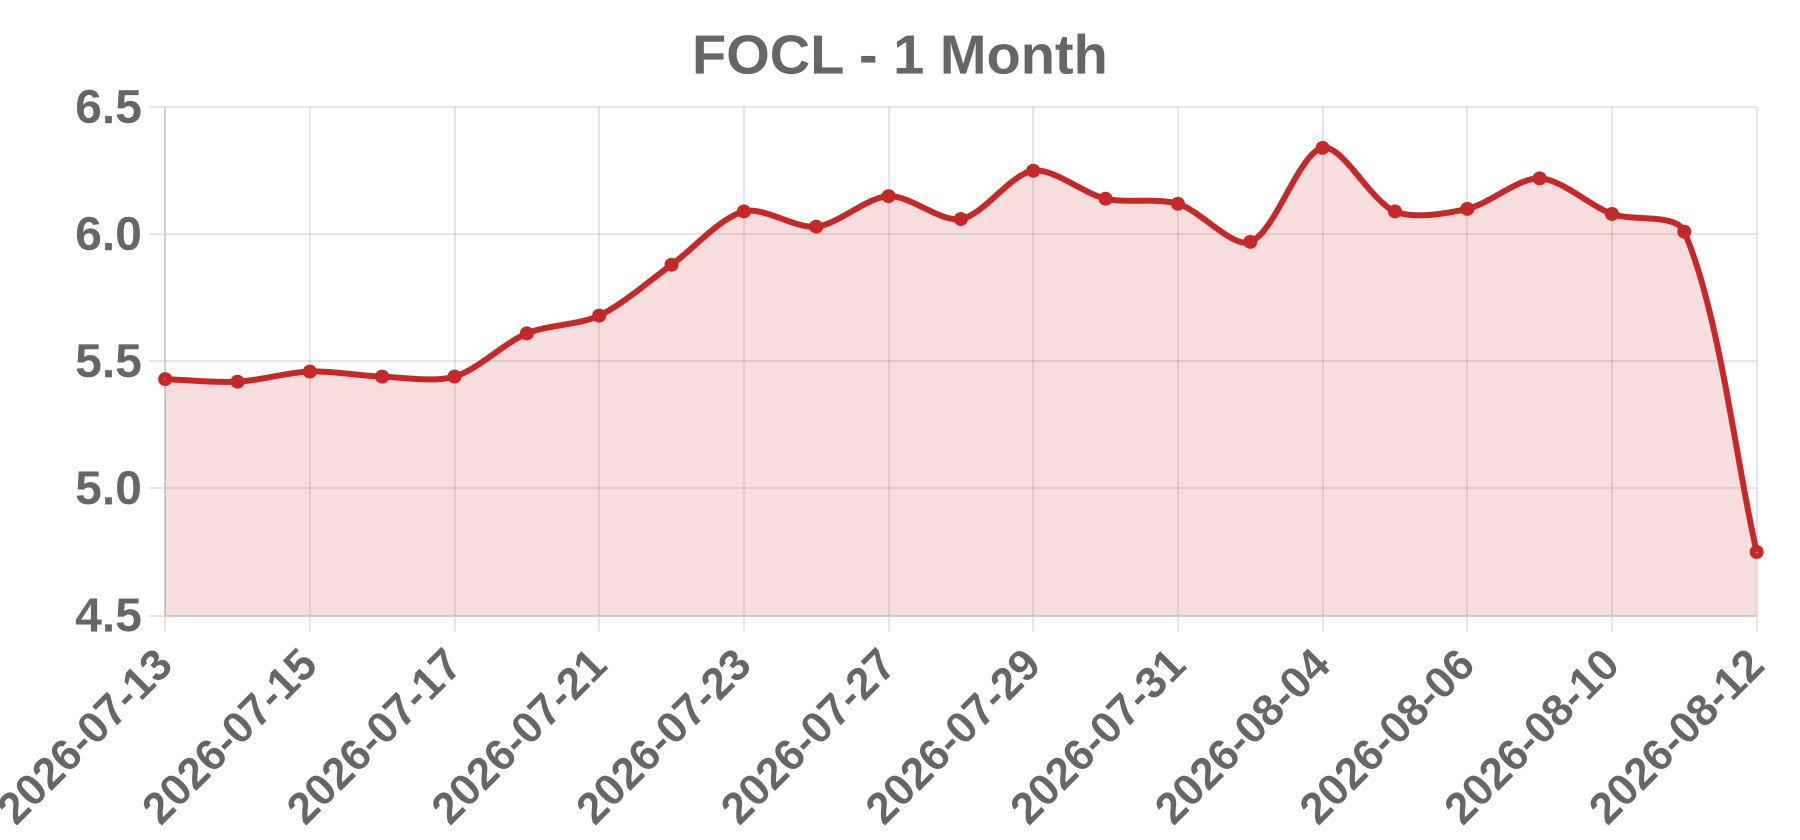
Business EDAP TMS S.A., doing business as FocalTherics (Nasdaq: FOCL), is a French medical technology company that develops, manufactures, and markets minimally invasive devices based on proprietary high-intensity focused ultrasound (HIFU) technology. Its flagship Focal One Robotic HIFU platform delivers personalized focal therapy for prostate cancer and other urological conditions. HQ: Lyon, France and Austin, Texas.
Today’s take FOCL fell 20.97% to close exactly at $4.75 on Aug 12, 2026, the session after FocalTherics priced an underwritten offering of 8,425,000 ADSs at $4.75 per ADS (~$40M gross proceeds), a ~21% discount to the prior $6.01 close. The stock opened at the offer price, ranged $4.67–$5.01, and settled at the placement price, confirming the offering became the session's anchor. Volume surged to ~1.29M shares versus a ~40–60K daily average. The same Aug 11 announcement carried preliminary Q2 2026 HIFU continuing-segment revenue of $12.7–$13.2M (+34–39% YoY, gross margin 54–56%), but that was ~15–16% below the ~$15.1M analyst consensus (Dow Jones flagged a 'soft 2Q outlook'), compounding the dilution shock. ESWL and Distribution segments were reclassified as discontinued operations, and full Q2 results were scheduled for Aug 13. With only ~$21.5M in cash, the discounted raise signals balance-sheet strain; a 30-day greenshoe (up to 1,263,750 additional ADSs) and the pending earnings print kept overhang elevated.
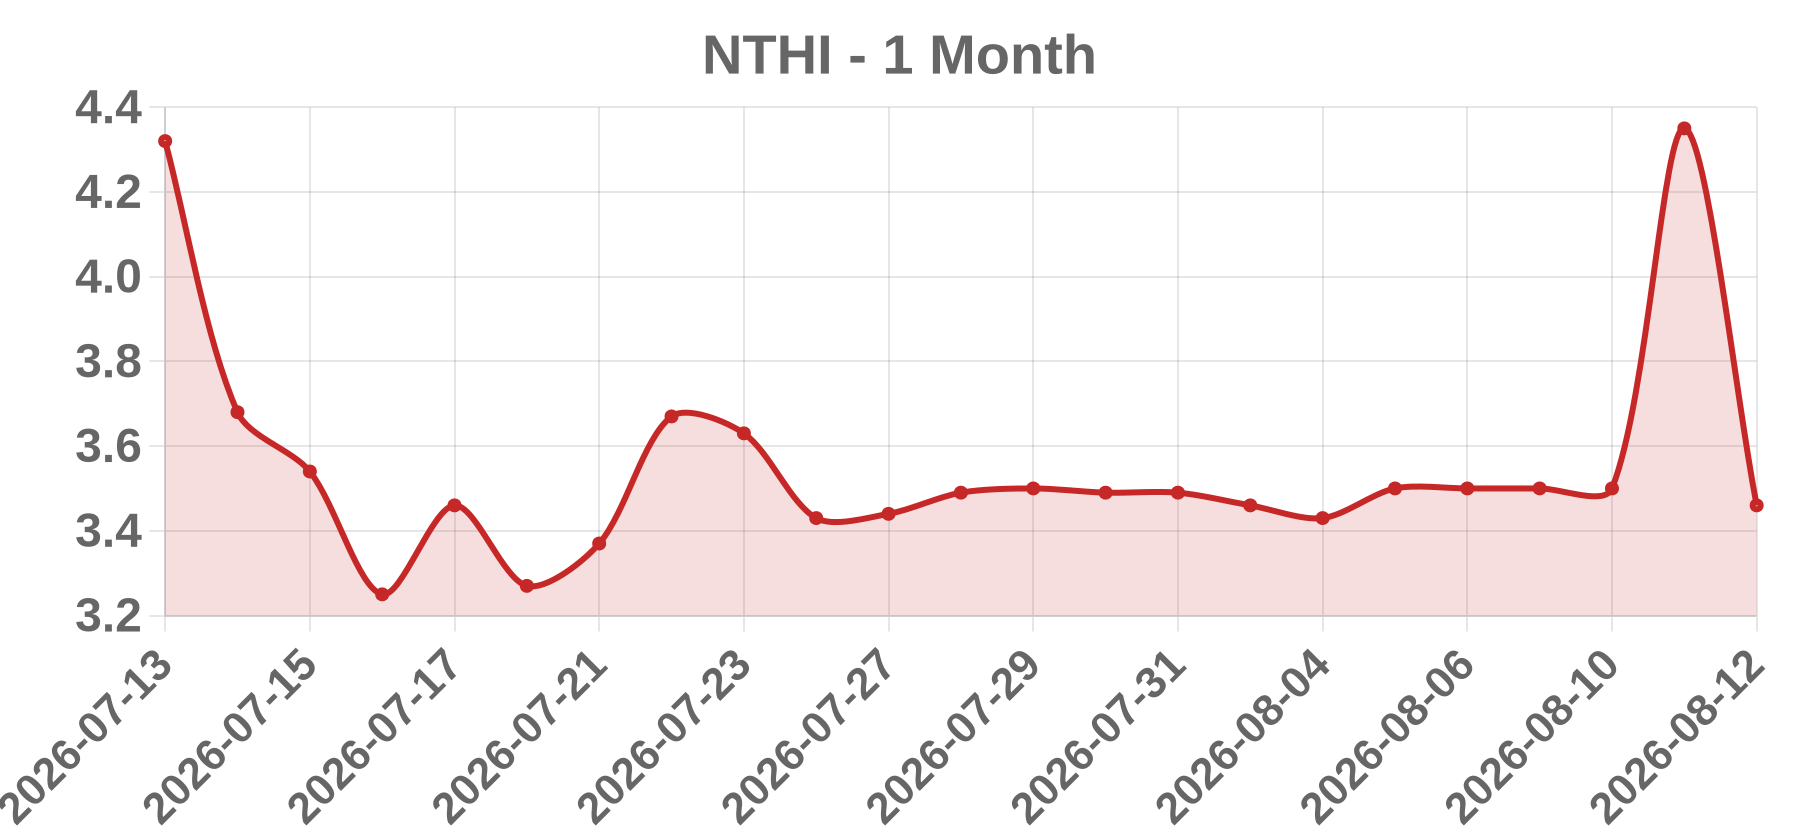
Business NeOnc Technologies Holdings, Inc. (Nasdaq: NTHI) is a clinical-stage biopharmaceutical company headquartered in Calabasas, California, developing intranasal CNS cancer therapies designed to bypass the blood-brain barrier. Lead candidates are NEO100 (ultra-pure perillyl alcohol) and NEO212, licensed from the University of Southern California; the company has no approved products and no revenue.
Today’s take On Aug 12, 2026, NeOnc released positive topline Phase 2a data for intranasal NEO100 in recurrent IDH1-mutant high-grade glioma: the NEO100-01 study met its primary endpoint with six-month progression-free survival (PFS-6) of 48.9% (95% CI 26.3-68.1) vs a pre-specified 20% standard-of-care benchmark (p=0.0047), median overall survival of 26.09 months, and 86.7% 6-month OS. Despite the apparent beat, shares reversed from a pre-market surge (~$5.24, +19%) and an intraday high of $4.74 to close at $3.46, down 20.46% on ~1.09M shares — a textbook sell-the-news unwind. Drivers: (1) 48.9% PFS-6 was barely above the ~44% six-month PFS the company had already disclosed in earlier historical observations, leaving little incremental surprise; (2) the stock had run +24.29% on 8/11 on ~1.04M shares (~20x normal volume) of event speculation; (3) the trial was a 24-patient, single-arm, open-label study not powered as confirmatory, with the FDA registrational path still undefined; and (4) Q2 2026 cash was only ~$2.0M, raising dilution fears. Short interest of ~522K shares (~25% of float per Finviz) amplified both the squeeze-up and the reversal.
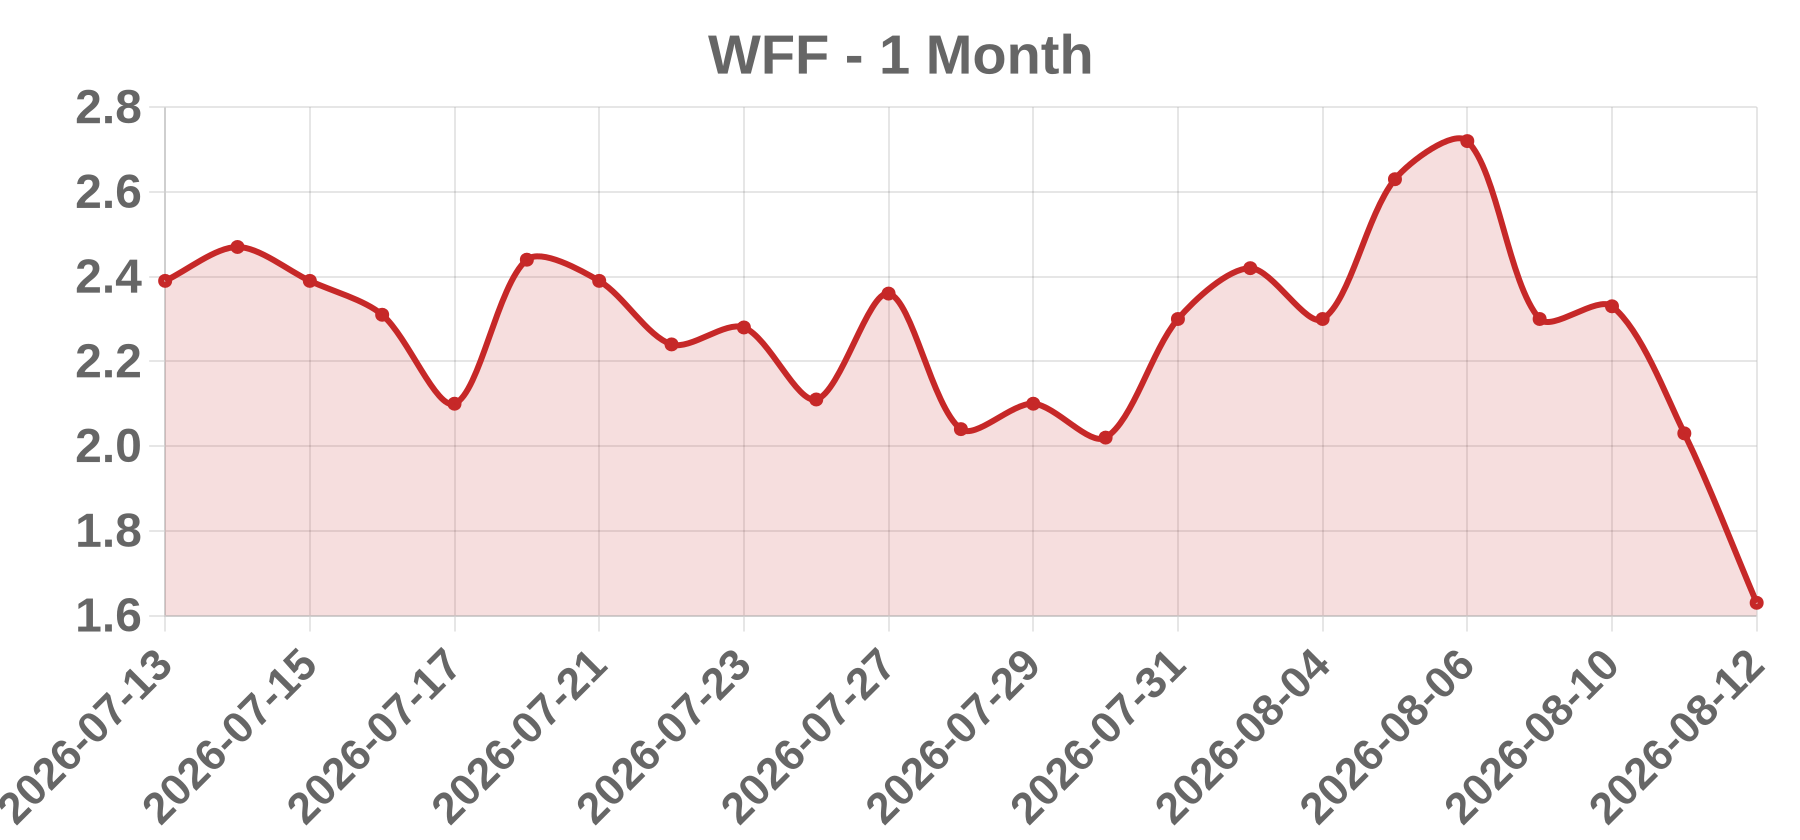
Business WF Holding Limited (NASDAQ: WFF) is a Cayman Islands-incorporated holding company headquartered in Shah Alam, Selangor, Malaysia. Through its subsidiary Win-Fung Fibreglass Sdn. Bhd., it manufactures and supplies fiberglass reinforced plastic (FRP) products — filament-wound and molded tanks, pipes, ducts, gratings, and custom parts — for the chemical processing, water/wastewater treatment, oil & gas, and power generation industries across Malaysia, Singapore, Australia, China, and South Asia. Listed on the Nasdaq Capital Market since March 2025, the company completed a 1-for-5 reverse share split effective April 13, 2026.
Today’s take WFF fell 19.70% to $1.63 on Aug 12, 2026 (open $1.86; intraday range $1.54–$2.04) on ~1.02–1.05M shares, the third straight down session after a retail-driven mania on Aug 7 that spiked to a 52-week high of $10.53 before closing at $2.30 (-15.56%) on 31.1M shares versus a ~576K 65-day average. The Aug 7 pump followed a July 30 standby equity purchase agreement (6-K filed July 31, 2026) letting an institutional investor buy up to $30M of shares over 24 months at the lower of $1.01 or 50% of the lowest 180-day close (floor $0.10) — a deeply dilutive structure that caps rallies and pressures the stock as it falls. The unwind continued Aug 10–12: $2.33 (+1.3%), $2.03 (-12.88%), then $1.63 (-19.70%). No new 6-K, 8-K, or earnings release appeared Aug 11–12, so the move was a pure technical reversal of the Aug 7 spike. Fundamentals offered no support: TTM revenue $7.40M, net loss -$4.77M (EPS -$0.97), market cap ~$8.2M, and Barron's Stock Grader has rated it SELL since Jan 1, 2026.